





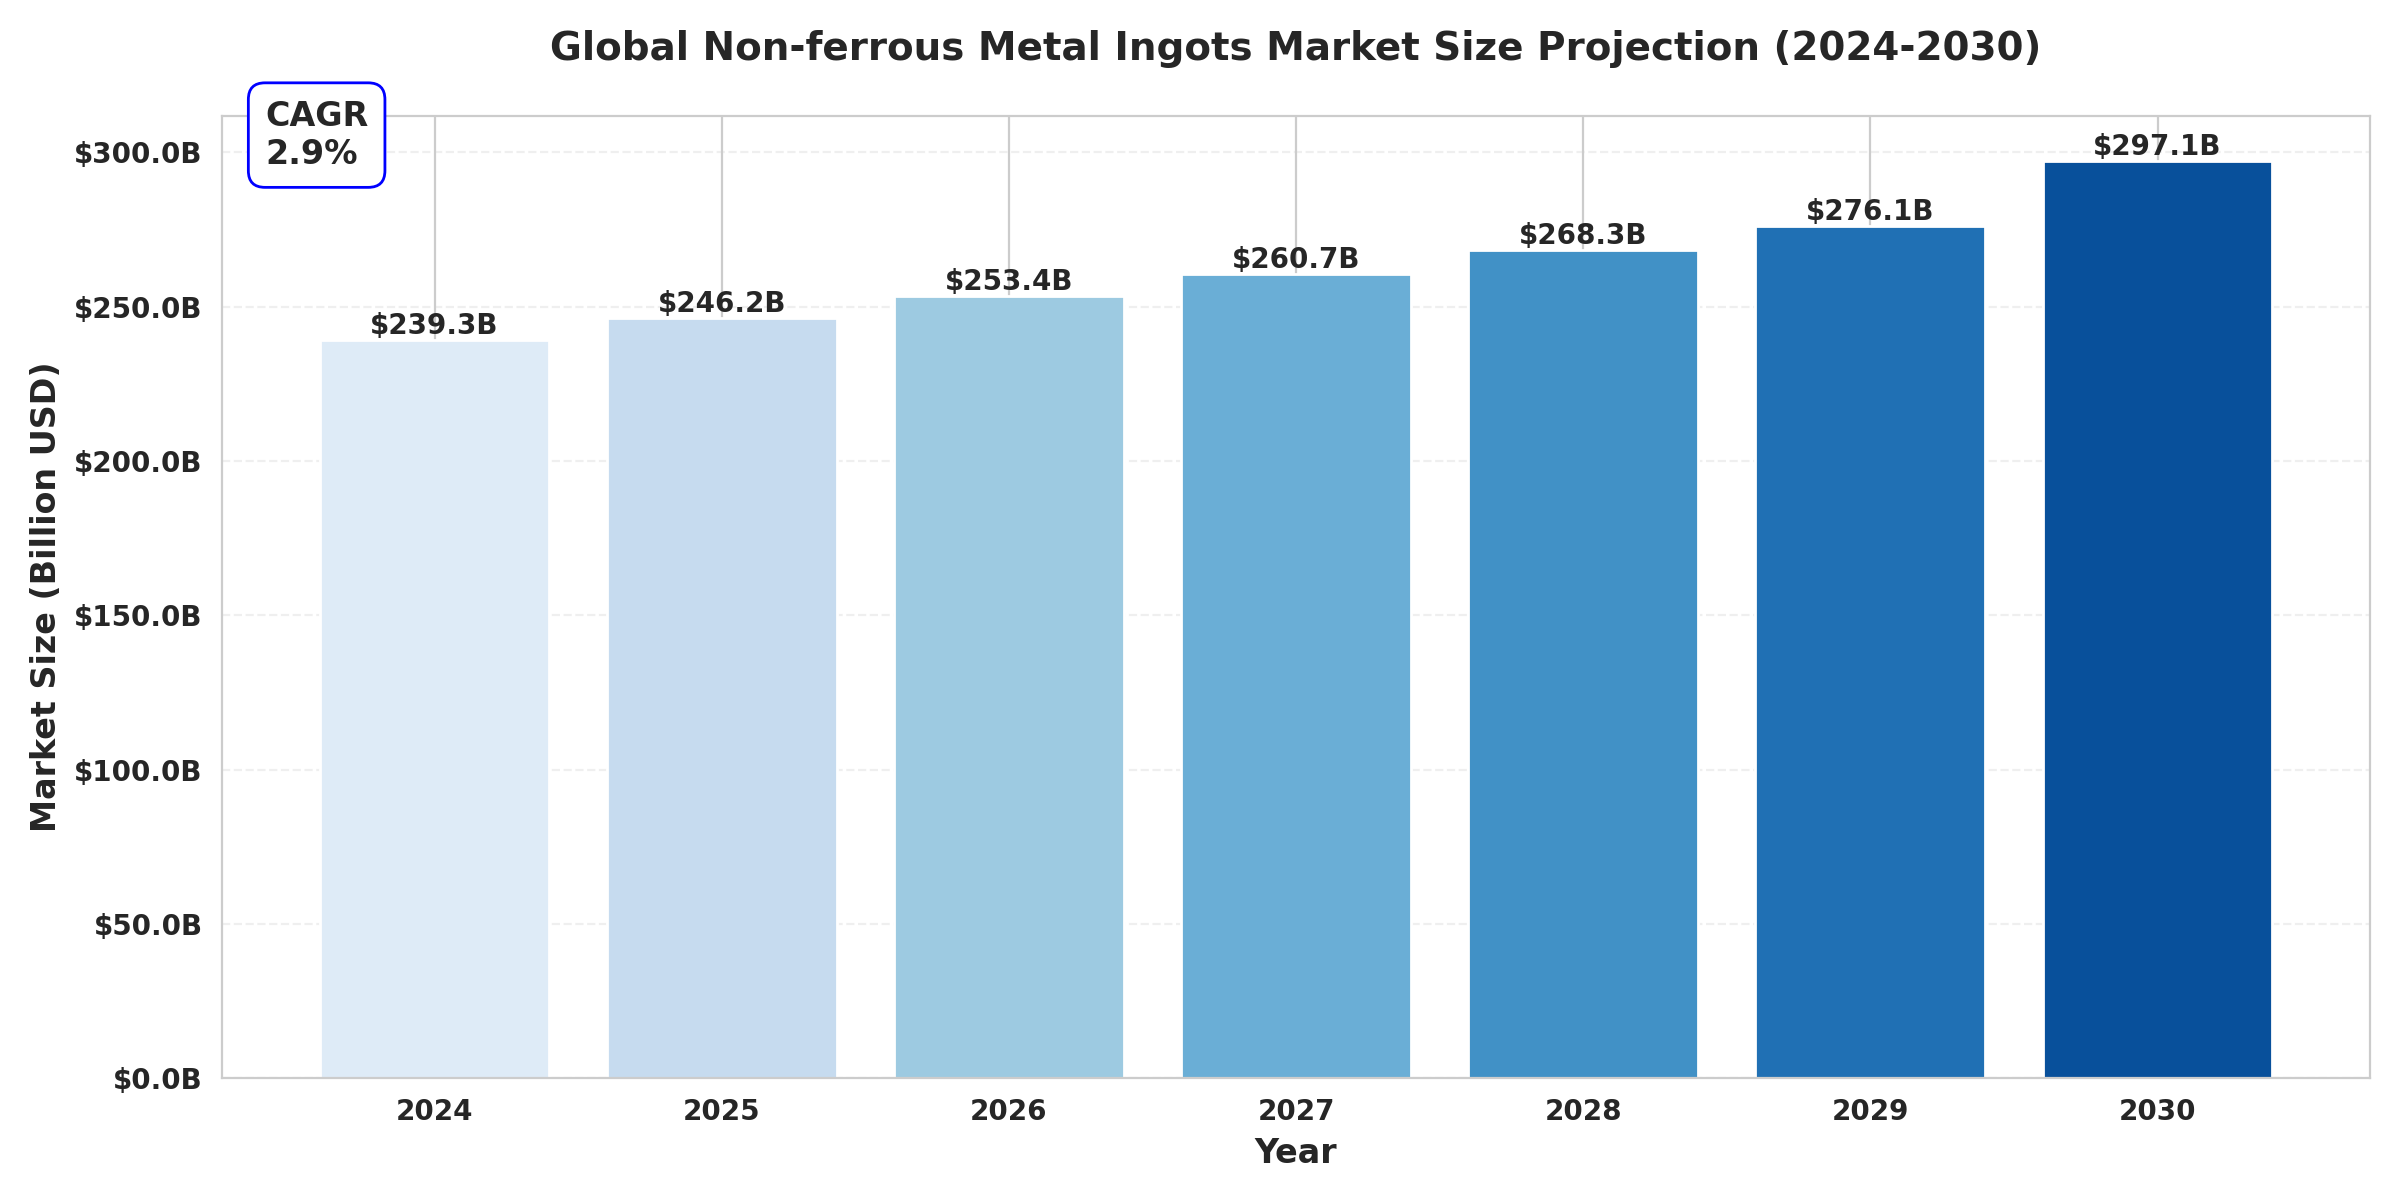
The Global Non-ferrous Metal Ingots Market was valued at USD 239.3 billion in 2025 and is projected to reach USD 297.1 billion by 2034, exhibiting a Compound Annual Growth Rate (CAGR) of 2.9% during the forecast period (2025‑2034).
Key manufacturers include China Hongqiao Group, United Company RUSAL, Rio Tinto Group, Aluminum Corporation of China Limited (Chalco), Norsk Hydro ASA, Glencore International AG, BHP Billiton, Hindalco Industries, Vedanta Resources, and Sumitomo Metal Mining. In 2023, the top five players captured a combined revenue share of approximately 45%.
This report delivers a comprehensive view of the Global Non-ferrous Metal Ingots Market, combining quantitative data and qualitative insights to support business strategy, competitive assessment, and market positioning.
- Global Non-ferrous Metal Ingots Market Revenue, 2019‑2024, 2025‑2034 (USD millions)
- Global Non-ferrous Metal Ingots Market Sales, 2019‑2024, 2025‑2034 (Kiloton)
- Global top five Non-ferrous Metal Ingots companies in 2023 (%)
We surveyed manufacturers, suppliers, distributors, and industry experts to capture sales, revenue, demand shifts, pricing trends, product mix, recent developments, and risk factors.
Total Market by Segment:
Global Non-ferrous Metal Ingots Market, by Type, 2019‑2024, 2025‑2034 (USD millions) & (Kiloton)
Global Non-ferrous Metal Ingots Market Segment Percentages, by Type, 2023 (%)
- Copper Ingots
- Lead Ingots
- Zinc Ingots
- Others
Global Non-ferrous Metal Ingots Market, by Application, 2019‑2024, 2025‑2034 (USD millions) & (Kiloton)
Global Non-ferrous Metal Ingots Market Segment Percentages, by Application, 2023 (%)
- Electronic Product
- Chemical Industry
- Aerospace
- Others
Global Non-ferrous Metal Ingots Market, By Region and Country, 2019‑2024, 2025‑2034 (USD millions) & (Kiloton)
Global Non-ferrous Metal Ingots Market Segment Percentages, By Region and Country, 2023 (%)
- North America (United States, Canada, Mexico)
- Europe (Germany, France, United Kingdom, Italy, Spain, Rest of Europe)
- Asia-Pacific (China, India, Japan, South Korea, Australia, Rest of APAC)
- The Middle East and Africa (Middle East, Africa)
- South and Central America (Brazil, Argentina, Rest of SCA)
Competitor Analysis
The report also provides analysis of leading market participants including:
- Key companies Non-ferrous Metal Ingots revenues in global market, 2019‑2024 (Estimated), (USD millions)
- Key companies Non-ferrous Metal Ingots revenues share in global market, 2023 (%)
- Key companies Non-ferrous Metal Ingots sales in global market, 2019‑2024 (Estimated), (Kiloton)
- Key companies Non-ferrous Metal Ingots sales share in global market, 2023 (%)
Key players include:
- China Hongqiao Group
- United Company RUSAL
- Rio Tinto Group
- Aluminum Corporation of China Limited (Chalco)
- Norsk Hydro ASA
- Glencore International AG
- BHP Billiton
- Hindalco Industries
- Vedanta Resources
- Sumitomo Metal Mining
🔟 1. China Hongqiao Group
Headquarters: Shanghai, China
Key Offering: Copper Ingots, Recycled Copper
China Hongqiao has cemented its position as the largest copper producer globally, with an integrated chain from mining to smelting. Recent capital injections have expanded its smelting capacity by 15% and accelerated the adoption of energy‑efficient blast furnaces.
Sustainability & Growth Initiatives:
- Investing in carbon capture and storage to reduce smelting emissions.
- Expanding recycled copper streams to meet tightening environmental regulations.
- Collaborating with logistics partners to shorten the supply chain and lower transport emissions.
9️⃣ 2. United Company RUSAL
Headquarters: Moscow, Russia
Key Offering: Zinc Ingots, Lead Ingots
RUSAL remains the world’s leading zinc producer, with a diversified portfolio spanning mining, smelting, and alloy production. The company’s strategic acquisition of a zinc refinery in the United States has broadened its footprint in the North American market.
Sustainability & Growth Initiatives:
- Deploying advanced smelting technologies to cut sulfur dioxide emissions.
- Investing in digital monitoring of energy consumption across its plants.
- Partnering with recycling firms to increase the share of secondary zinc.
8️⃣ 3. Rio Tinto Group
Headquarters: London, United Kingdom
Key Offering: Aluminium Ingots, Copper Ingots
Rio Tinto’s aluminium division drives the majority of its revenue, operating a network of bauxite mines and alumina refineries across Australia and Guinea. Recent investments in green aluminium production—using renewable electricity—position the company to meet future demand for low‑carbon alloys.
Sustainability & Growth Initiatives:
- Expanding renewable energy procurement to power smelting operations.
- Implementing closed‑loop water recycling in aluminium plants.
- Launching a joint venture with a European recycling firm to enhance secondary aluminium supply.
7️⃣ 4. Aluminum Corporation of China Limited (Chalco)
Headquarters: Beijing, China
Key Offering: Aluminium Ingots, Bauxite
Chalco operates a vertically integrated aluminium supply chain, from bauxite mining to aluminium ingot production. The company’s recent expansion into the high‑purity aluminium segment supports its aerospace and automotive customers.
Sustainability & Growth Initiatives:
- Adopting electrolytic aluminium smelting powered by hydropower.
- Investing in research on lightweight aluminium alloys.
- Strengthening partnerships with battery manufacturers to secure a steady demand for aluminium casings.
6️⃣ 5. Norsk Hydro ASA
Headquarters: Oslo, Norway
Key Offering: Aluminium Ingots, Aluminium Recycling
Norsk Hydro is a leading player in both primary aluminium production and recycling. Its focus on circular economy principles is reflected in a 25% increase in recycled aluminium output over the past two years.
Sustainability & Growth Initiatives:
- Expanding its recycling network across Europe.
- Investing in hydrogen‑based smelting to reduce carbon intensity.
- Partnering with automotive OEMs to supply lightweight, high‑strength aluminium alloys.
5️⃣ 6. Glencore International AG
Headquarters: Baar, Switzerland
Key Offering: Copper, Zinc, Lead Ingots
Glencore’s diversified portfolio spans mining, smelting, and trading. The company’s recent acquisition of a zinc smelter in the United States bolstered its North American presence.
Sustainability & Growth Initiatives:
- Implementing energy‑efficient smelting processes across its plants.
- Increasing the proportion of secondary metals in its portfolio.
- Launching a digital platform to track metal provenance and support responsible sourcing.
4️⃣ 7. BHP Billiton
Headquarters: Melbourne, Australia
Key Offering: Copper, Aluminium Ingots
BHP’s copper division operates the world’s largest copper mine, with a strong focus on sustainable mining practices. The company’s recent investment in a new copper smelter in Chile aims to secure a stable supply for the growing demand in electronics and renewable energy.
Sustainability & Growth Initiatives:
- Deploying low‑emission mining equipment.
- Investing in water‑recycling technologies.
- Partnering with battery manufacturers to provide high‑purity copper.
3️⃣ 8. Hindalco Industries
Headquarters: Mumbai, India
Key Offering: Aluminium Ingots, Copper Ingots
Hindalco’s aluminium division is a major supplier to the automotive and construction sectors in India. The company’s recent expansion of its smelting capacity by 12% is aimed at meeting the rising demand for aluminium in the electric vehicle market.
Sustainability & Growth Initiatives:
- Implementing renewable energy projects to power smelters.
- Increasing the use of recycled aluminium in its product mix.
- Collaborating with local governments to promote circular economy practices.
2️⃣ 9. Vedanta Resources
Headquarters: London, United Kingdom
Key Offering: Copper, Lead, Zinc Ingots
Vedanta’s diversified metal portfolio includes copper, lead, and zinc. The company’s recent joint venture with a European recycling firm has expanded its secondary metal sourcing.
Sustainability & Growth Initiatives:
- Adopting low‑carbon smelting technologies.
- Investing in digital traceability for metal supply chains.
- Expanding partnerships with battery manufacturers for copper supply.
1️⃣ 10. Sumitomo Metal Mining
Headquarters: Tokyo, Japan
Key Offering: Copper Ingots, Aluminium Ingots
Sumitomo’s integrated operations span mining, smelting, and alloy production. The company’s recent investment in a high‑purity copper smelter in Japan supports its commitment to meet the demands of the electronics sector.
Sustainability & Growth Initiatives:
- Deploying advanced smelting technologies to reduce energy consumption.
- Increasing the proportion of recycled metals in its production.
- Partnering with semiconductor manufacturers to secure a steady copper supply.
Download FREE Sample Report: https://www.24chemicalresearch.com/download-sample/292731/polyester-chip-market
Get Full Report Here: https://www.24chemicalresearch.com/reports/270428/global-nonferrous-metal-ingots-forecast-market-2024-2030-24
🌍 Outlook: The Future of Non-ferrous Metal Ingots
The market is experiencing a steady uptick driven by the electronics, chemical, and aerospace sectors. Demand for copper and aluminium is rising as electric vehicles and renewable energy infrastructure expand. At the same time, regulatory frameworks in the EU and the United States are tightening emissions standards, pushing producers toward cleaner smelting and increased recycling.
📈 Key Trends Shaping the Market:
- Acceleration of secondary metal sourcing to meet sustainability mandates.
- Investment in hydrogen‑based smelting to lower carbon footprints.
- Digitalization of supply chains for greater transparency and efficiency.
- Strategic alliances between metal producers and battery manufacturers.
Download FREE Sample Report: https://www.24chemicalresearch.com/download-sample/292731/polyester-chip-market
📊 Future Trends
Looking ahead, the market will see a shift toward high‑performance alloys tailored for lightweight automotive and aerospace applications. Digital traceability will become a standard, driven by regulatory demands for responsible sourcing. Geopolitical tensions and trade policies will continue to influence supply chains, creating opportunities for companies that can secure diversified sourcing strategies.
By 2034, the market is expected to reach USD 297.1 billion, with a balanced mix of primary and secondary metal production. Companies that invest in low‑carbon technologies, digital platforms, and circular economy partnerships will be best positioned to capture the growing demand.
Non-ferrous Metal Ingots Market – View in Detailed Research Report
- Top 10 Companies in the Carbon Black Pigments Market (2026): Market Leaders Driving Global Demand - October 11, 2026
- Top 10 Companies in the Antistatic Nylon Fibers Market (2026): Market Leaders Powering Global Innovation - October 11, 2026
- Top 10 Companies in the Phenylbenzimidazole Sulfonic Acid Market (2026): Market Leaders Powering Global Demand - October 11, 2026