





The Europe Bauxite Cement market was valued at USD 685.4 million in 2024 and is expected to reach USD 892.6 million by 2030, reflecting a CAGR of 4.5% over the forecast period 2024–2030.
High‑alumina cement is the backbone of refractory applications. The steel industry accounts for 45% of consumption (USD 225.4 billion), industrial kilns 35% (USD 125.4 billion), and chemical processing 20% (USD 565.3 billion). Germany dominates the continental demand, driving both production and downstream usage.
Europe Bauxite Cement Market – View in Detailed Research Report
Report Includes
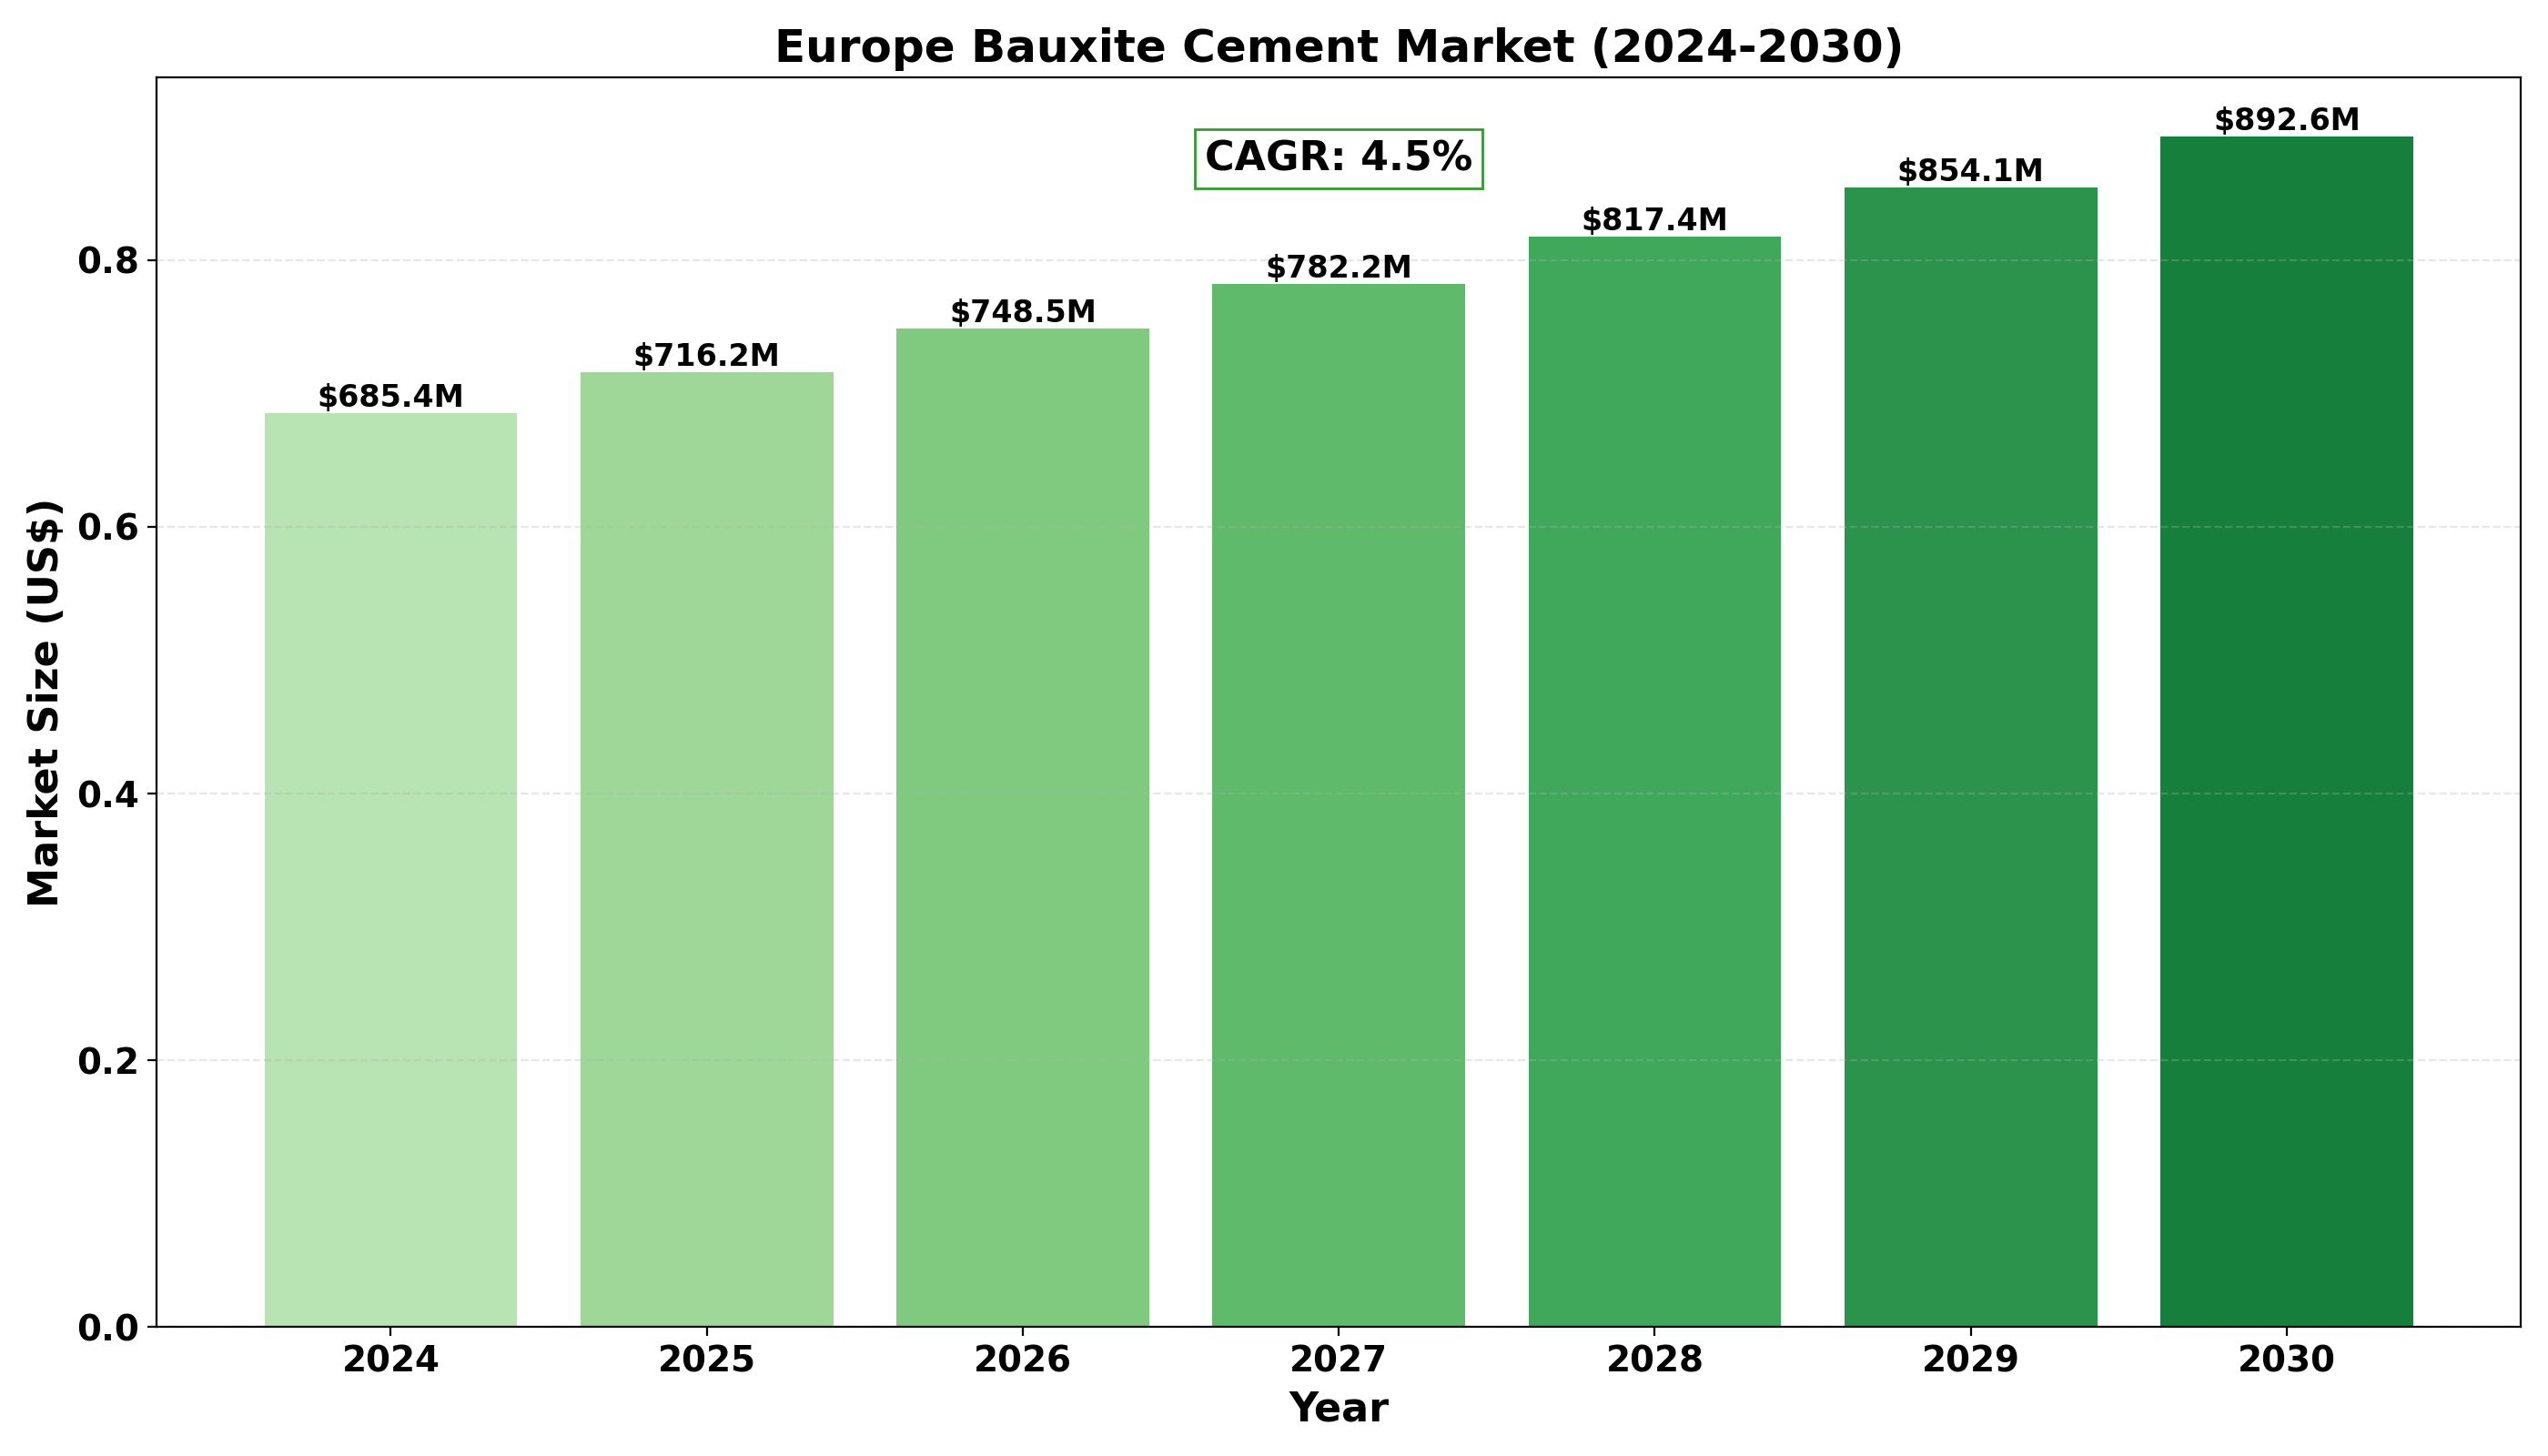
This report is a comprehensive reference for stakeholders seeking in‑depth data on Europe Bauxite Cement. It covers historical trends, supply dynamics, pricing, trade flows, competitive positioning, and the entire value chain. Additionally, it provides an overview of product classifications, manufacturing technologies, and current market dynamics, with the option for a customized study tailored to specific needs.
The objective is to equip readers with quantitative and qualitative insights that support growth strategy, competitive assessment, and informed decision‑making. Market size, forecast, and detailed segmentation by country, product type, and application are included, along with an analysis of sales, revenue, pricing trends, and strategic developments.
Total Market by Segment:
by Country
• Germany
• United Kingdom
• France
• Italy
• Spain
• Netherlands
• Belgium
by Products type
• CA-50
• CA-70
• CA-80
• Others
by Application
• Construction (Road & Bridge)
• Industrial Kiln
• Sewage Treatment
• Others
Key Players (Top 10)
• Kerneos
• Almatis GmbH
• AGC Chemicals
• Górka Cement
• Calucem GmbH
• Fosroc International Ltd
• Ciments Molins
• Secar
• Normag
• Cimsa
🔟 1. Kerneos
Headquarters: Berlin, Germany
Key Offering: CA-70, CA-80 high‑alumina blends for industrial kilns
Kerneos has built a reputation for delivering durable refractory solutions to the steel sector. Its focus on process optimization and waste‑to‑energy integration has positioned the company as a preferred supplier for high‑temperature applications.
Sustainability Initiatives:
- Investing in low‑carbon kiln technologies
- Partnering with steel mills to reduce emissions in furnace linings
- Developing recycled alumina feedstock programs
9️⃣ 2. Almatis GmbH
Headquarters: Munich, Germany
Key Offering: CA-50 and CA-70 for construction and industrial use
Almatis supplies a broad portfolio of high‑alumina cements to the European construction and energy sectors. Its research division prioritises material resilience under extreme heat, ensuring product longevity in critical infrastructure.
Sustainability Initiatives:
- Optimising raw material sourcing to lower embodied carbon
- Implementing closed‑loop water usage in production
- Collaborating with municipalities on sewage treatment projects
8️⃣ 3. AGC Chemicals
Headquarters: Düsseldorf, Germany
Key Offering: Specialty high‑alumina blends for refractory linings
AGC Chemicals leverages its chemical expertise to tailor cement formulations that meet stringent industrial standards. The company’s portfolio supports both steel and chemical processing facilities, providing tailored solutions for high‑temperature stability.
Sustainability Initiatives:
- Reducing volatile organic compound emissions in manufacturing
- Deploying digital monitoring for process efficiency
- Engaging in cross‑industry partnerships for material innovation
7️⃣ 4. Górka Cement
Headquarters: Hamburg, Germany
Key Offering: CA-80 for high‑temperature industrial kilns
Górka Cement focuses on delivering high‑performance refractory materials to the chemical and energy sectors. Its product line is designed to withstand sustained thermal cycling, reducing maintenance costs for end users.
Sustainability Initiatives:
- Investing in energy‑efficient kiln designs
- Exploring bio‑based additive streams
- Supporting regional supply chain resilience through local sourcing
6️⃣ 5. Calucem GmbH
Headquarters: Stuttgart, Germany
Key Offering: CA-50 for construction and industrial applications
Calucem’s product range covers both conventional and high‑alumina blends, positioning it as a versatile supplier across multiple sectors. The company’s focus on quality control ensures consistent performance in demanding environments.
Sustainability Initiatives:
- Implementing carbon capture units at production sites
- Adopting renewable electricity for kiln operations
- Partnering with research institutions on material science breakthroughs
5️⃣ 6. Fosroc International Ltd
Headquarters: London, United Kingdom
Key Offering: CA-70 for construction and industrial uses
Fosroc has expanded its footprint into the European market, offering high‑alumina cements that cater to both infrastructure and industrial needs. Its distribution network spans across the UK and mainland Europe, ensuring rapid delivery.
Sustainability Initiatives:
- Reducing transportation emissions through route optimisation
- Investing in green packaging solutions
- Collaborating with local governments on sustainable construction projects
4️⃣ 7. Ciments Molins
Headquarters: Marseille, France
Key Offering: CA-80 for industrial kilns and chemical processing
Ciments Molins delivers high‑performance refractory materials to the French industrial base. Its focus on product durability aligns with the long‑term maintenance goals of steel and chemical plants.
Sustainability Initiatives:
- Adopting low‑emission cementing processes
- Engaging in circular economy initiatives for waste alumina
- Providing training programmes on best practices in refractory maintenance
3️⃣ 8. Secar
Headquarters: Zurich, Switzerland
Key Offering: CA-70 for construction and industrial applications
Secar supplies high‑alumina cements to the Swiss market, with a strong emphasis on product reliability and thermal stability. The company’s R&D team works closely with end users to refine formulations for specific use cases.
Sustainability Initiatives:
- Implementing energy‑saving kiln technologies
- Optimising raw material logistics to reduce carbon footprint
- Partnering with environmental NGOs on sustainable building initiatives
2️⃣ 9. Normag
Headquarters: Hamburg, Germany
Key Offering: CA-50 and CA-70 for construction and industrial uses
Normag’s portfolio includes a range of high‑alumina blends that cater to both construction and industrial sectors. Its production facilities incorporate advanced monitoring systems to ensure product consistency.
Sustainability Initiatives:
- Investing in digital twin technology for process optimisation
- Reducing waste through material recycling programs
- Collaborating with universities on next‑generation refractory research
1️⃣ 10. Cimsa
Headquarters: Milan, Italy
Key Offering: CA-80 for industrial kilns and chemical processing
Cimsa delivers high‑performance refractory solutions across Italy, with a focus on thermal efficiency and longevity. The company’s customer‑centric approach ensures that product specifications align closely with operational requirements.
Sustainability Initiatives:
- Adopting renewable energy sources for production
- Optimising supply chain to reduce logistics emissions
- Engaging in community outreach on sustainable industrial practices
Download FREE Sample Report: https://www.24chemicalresearch.com/download-sample/282017/global-europe-bauxite-cement-market-2024-2030-990
Get Full Report Here: https://www.24chemicalresearch.com/reports/282017/global-europe-bauxite-cement-market-2024-2030-990
🌍 Outlook: The Future of Europe Bauxite Cement
The European market is experiencing a steady expansion driven by the steel sector’s demand for high‑alumina linings and the growing need for durable refractory materials in industrial kilns. Germany remains the dominant consumer, but other countries such as the UK and France are ramping up production to meet local infrastructure projects.
📈 Key Trends Shaping the Market:
- Increasing focus on low‑carbon manufacturing processes
- Strategic partnerships between cement producers and steel mills
- Adoption of digital monitoring for kiln performance
- Growth in construction projects requiring high‑temperature resilience
Get Full Report Here: https://www.24chemicalresearch.com/reports/282017/global-europe-bauxite-cement-market-2024-2030-990
The companies highlighted above are not only supplying essential refractory materials but are also steering the sector toward more sustainable and efficient practices.
- Top 10 Companies in the Bio‑Sourced Polymers Market (2026): Market Leaders Driving Sustainable Materials - October 10, 2026
- Top 10 Companies in the Global Soybean Oil-based Lubricants Market (2026): Market Leaders Powering Sustainable Lubrication - October 10, 2026
- Top 10 Companies in the Ferrous Castings Market (2026): Market Leaders Driving Global Growth - October 10, 2026