





MARKET INSIGHTS
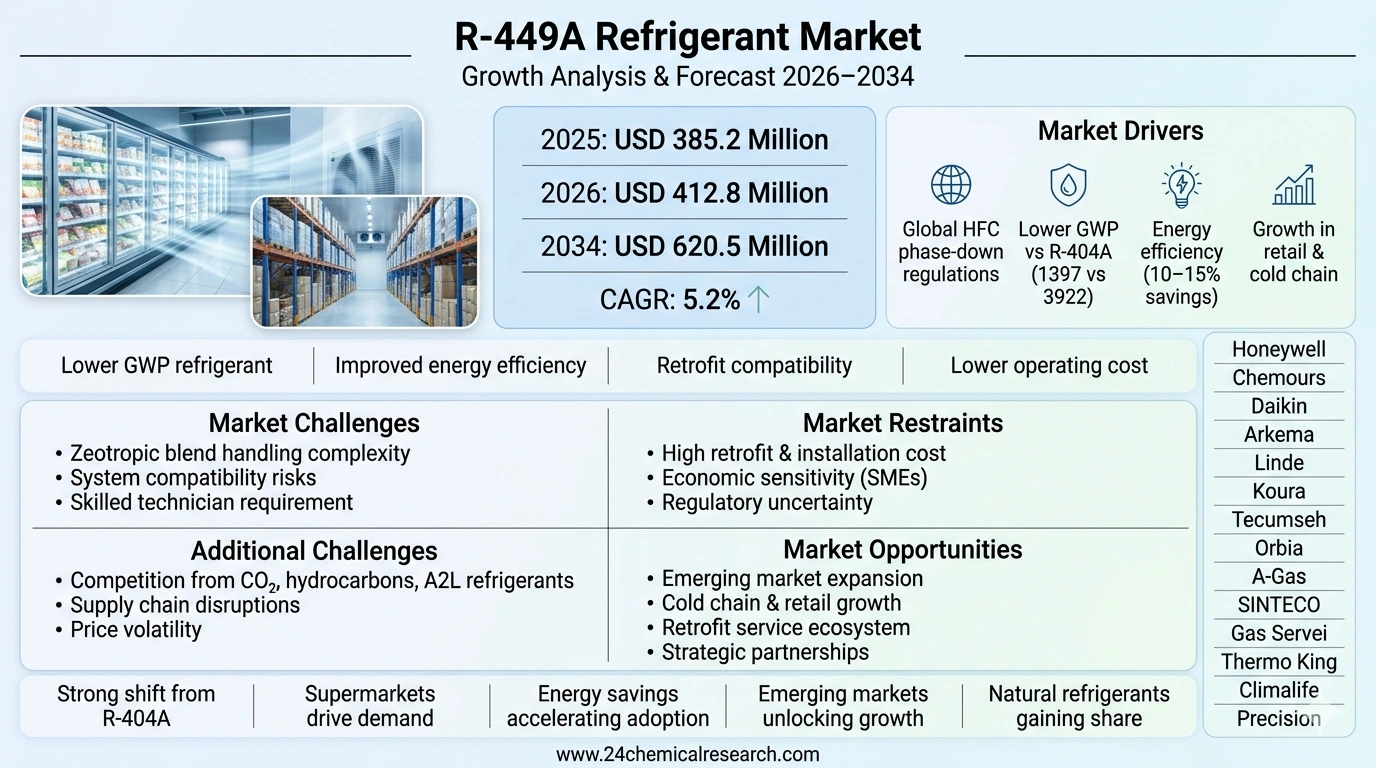
The global R‑449a refrigerant market size was valued at USD 385.2 million in 2025. The market is projected to grow from an estimated USD 412.8 million in 2026 to reach USD 620.5 million by 2034, exhibiting a compound annual growth rate (CAGR) of 5.2% during the forecast period.
R‑449a, commercially known as Solstice® N40 by Honeywell, is an environmentally sustainable, non‑ozone depleting hydrofluoroolefin (HFO) blend refrigerant designed to offer a low global warming potential (GWP) of approximately 1,397. It is widely recognized as a superior, energy‑efficient replacement for R‑404A and R‑507 in various medium and low‑temperature refrigeration applications. This refrigerant is classified as an A1 refrigerant by ASHRAE, indicating its lower toxicity and higher flammability safety rating.
The market is experiencing significant growth, primarily driven by stringent global environmental regulations such as the Kigali Amendment to the Montreal Protocol and the European Union’s F‑Gas Regulation, which mandate the phasedown of high‑GWP refrigerants. The transition towards sustainable cooling solutions in the commercial refrigeration sector, including supermarkets and cold storage warehouses, is a key factor. However, the market faces challenges such as the higher initial cost of HFO‑based refrigerants compared to traditional options and the need for system retrofitting. Leading players like Honeywell, Chemours, and Daikin are actively expanding their production capacities and product portfolios to capitalize on this regulatory‑driven demand.
MARKET DRIVERS
Global Regulatory Push Towards Low‑GWP Alternatives
Global demand for R‑449a is largely driven by regulatory mandates that phase out hydrofluorocarbons (HFCs) with high GWP. R‑449a’s markedly lower GWP of 1,397 compared to older refrigerants like R‑404A (GWP 3,922) positions it as a leading drop‑in or near‑drop‑in replacement in commercial refrigeration systems.
Energy Efficiency and Operational Cost Savings
Beyond compliance, R‑449a offers energy efficiency improvements of up to 10‑15% over R‑404A in medium and low‑temperature applications, translating into lower electricity consumption and operational expenditures. This economic benefit provides a compelling business case for retrofitting existing systems and specifying R‑449a for new installations.
➤ The transition is not just about compliance; it’s a strategic move towards more sustainable and cost‑effective operations. System manufacturers are now pre‑charging new units with R‑449a as a standard, reinforcing its market position.
Additionally, the expanding organized retail sector and the growing cold‑chain logistics industry for pharmaceuticals and perishable foods are creating a steady stream of new equipment installations that favor modern, efficient refrigerants like R‑449a.
MARKET CHALLENGES
Technical and Compatibility Hurdles
R‑449a is marketed as a drop‑in replacement, yet its zeotropic blend can lead to fractionation if not handled correctly during charging or in the event of a leak. This requires technicians to have specialized training and equipment, increasing service complexity and cost. Compatibility with existing lubricants and components must also be verified, as incompatibility can lead to reduced efficiency or equipment failure.
Other Challenges
Competition from Alternative Refrigerants
R‑449a competes with a crowded field of low‑GWP alternatives, including A2L mildly flammable refrigerants like R‑454C and natural refrigerants such as CO₂ (R‑744) and hydrocarbons. The growing acceptance of A2Ls, which have even lower GWPs, presents a significant challenge as safety standards evolve to accommodate them. Additionally, momentum behind natural refrigerant solutions in certain regions diverts investment away from HFO blends.
Price Volatility and Supply Chain Constraints
The market is susceptible to price fluctuations driven by the cost of HFO feedstocks and geopolitical factors affecting chemical production. Supply chain disruptions can lead to shortages, causing project delays and encouraging end‑users to consider alternative options, thereby fragmenting the market.
MARKET RESTRAINTS
High Initial Investment and Economic Uncertainty
Converting existing R‑404A systems to R‑449a requires significant capital expenditure, which can be prohibitive for small and medium‑sized enterprises, especially in a challenging economic climate. The higher cost of R‑449a compared to traditional refrigerants creates a double financial barrier that can slow adoption during periods of economic downturn or high inflation.
Navigating Evolving Regulatory Landscapes
Regulatory fragmentation across countries and regions creates uncertainty for multinational corporations and OEMs. The possibility that future regulations may skip over HFO blends like R‑449a in favor of ultra‑low GWP options can cause hesitation in long‑term investment decisions.
MARKET OPPORTUNITIES
Expansion in Emerging Economies
Rapid urbanization, industrialization, and rising disposable incomes in Asia‑Pacific, Latin America, and the Middle East are creating vast markets for new commercial refrigeration systems. Many of these countries are beginning to enact their own HFC phasedown schedules under the Kigali Amendment, presenting a greenfield opportunity for R‑449a to become the refrigerant of choice in new installations, bypassing retrofit challenges.
Innovation in Service and Retrofitting Technologies
The complexity of retrofitting existing systems opens a major opportunity for service‑based business models and technological innovation. Companies that develop streamlined retrofit protocols, advanced training programs for technicians, and diagnostic tools tailored for R‑449a systems can capture a significant share of the aftermarket. Innovations in leak detection and monitoring technologies that address the challenges of zeotropic blends can enhance system reliability and build confidence in R‑449a, accelerating its adoption across the installed base.
Strategic Partnerships and Consolidation
Collaborative efforts between chemical manufacturers, OEMs, and large end‑users to develop standardized solutions and promote the benefits of R‑449a can help consolidate its market position against competing alternatives. Mergers and acquisitions within the refrigerant industry can optimize production and distribution networks, improving availability and potentially reducing costs for end‑users over the long term.
R‑449aRefrigerant Market – View in Detailed Research Report
Top 10 Companies in the R‑449a Refrigerant Market (2026)
1️⃣ Honeywell International Inc.
Headquarters: Charlotte, North Carolina, USA
Key Offering: Solstice® N40, OEM integration kits, retrofit solutions
Honeywell has been at the forefront of HFO development, leveraging its extensive R&D and manufacturing footprint to deliver Solstice® N40 as a drop‑in replacement for high‑GWP refrigerants. The company’s focus on product reliability and safety, combined with a robust global distribution network, has positioned it as the benchmark for sustainable refrigeration.
Sustainability & Growth Initiatives:
- Expansion of production capacity in North America and Europe to meet rising demand.
- Investment in advanced leak‑detection and monitoring technologies.
- Strategic partnership with OEMs to pre‑charge new units with R‑449a.
2️⃣ The Chemours Company
Headquarters: Wilmington, Delaware, USA
Key Offering: Opteon® XP40, custom blend services, technical support
Chemours has positioned itself as a leader in low‑GWP refrigerants with its Opteon® XP40, a high‑purity HFO blend that delivers superior energy performance. Its strong patent portfolio and technical expertise enable it to maintain a competitive edge in both new installations and retrofit markets.
Sustainability & Growth Initiatives:
- Scaling production in key markets to secure long‑term supply contracts.
- Development of application‑specific formulations for industrial and commercial use.
- Collaboration with regulatory bodies to streamline compliance processes.
3️⃣ Daikin Industries Ltd.
Headquarters: Tokyo, Japan
Key Offering: R‑449a‑based compressor lines, retrofit kits, energy‑monitoring solutions
Daikin’s global presence and deep integration into HVACR manufacturing make it a critical player in the adoption of R‑449a. The company’s focus on energy efficiency and its extensive dealer network support rapid deployment across diverse markets.
Sustainability & Growth Initiatives:
- Investment in R‑449a production facilities in Asia‑Pacific.
- Launch of a comprehensive training program for technicians on zeotropic blend handling.
- Partnerships with local governments to promote low‑GWP solutions in commercial refrigeration.
4️⃣ Arkema S.A.
Headquarters: Paris, France
Key Offering: Custom HFO blends, safety‑certified lubricants, OEM integration services
Arkema’s expertise in advanced fluorochemical synthesis allows it to offer tailored HFO blends that meet stringent safety and performance criteria, making it a preferred supplier for OEMs in Europe and beyond.
Sustainability & Growth Initiatives:
- Development of ultra‑high‑purity grades for demanding industrial applications.
- Collaboration with European regulators to align product specifications with upcoming F‑Gas regulations.
- Expansion of regional production facilities to reduce lead times.
5️⃣ Linde A.G.
Headquarters: Dublin, Ireland
Key Offering: High‑purity R‑449a, industrial gas distribution, OEM support
Linde’s extensive gas distribution network and commitment to low‑carbon solutions position it as a key supplier for large‑scale commercial refrigeration projects.
Sustainability & Growth Initiatives:
- Strategic partnerships with HVACR OEMs to embed R‑449a in new equipment.
- Investment in digital supply‑chain solutions to improve inventory accuracy.
- Commitment to reducing CO₂ emissions across its production facilities.
6️⃣ Koura Global (Orbia)
Headquarters: London, United Kingdom
Key Offering: Low‑GWP refrigerant blends, service‑centered retrofit solutions, technical training
As a subsidiary of Orbia, Koura Global leverages its expertise in gas and refrigerant production to deliver high‑quality R‑449a blends tailored for commercial and industrial applications.
Sustainability & Growth Initiatives:
- Expansion of production capacity in the Middle East to support growing demand.
- Development of a certification program for technicians handling zeotropic blends.
- Collaboration with local OEMs to promote energy‑efficient refrigeration.
7️⃣ Tecumseh Products Company
Headquarters: South Bend, Indiana, USA
Key Offering: R‑449a charging systems, diagnostic tools, aftermarket support
Tecumseh’s focus on service‑centric solutions positions it as a trusted partner for retrofits, offering advanced charging equipment and real‑time monitoring.
Sustainability & Growth Initiatives:
- Launch of a mobile training platform for field technicians.
- Investment in sensor technology for leak detection.
- Partnerships with OEMs to pre‑charge new units with R‑449a.
8️⃣ Orbia (Mexico)
Headquarters: Mexico City, Mexico
Key Offering: Low‑GWP refrigerant blends, OEM integration, distribution services
Orbia’s regional manufacturing footprint enables it to supply R‑449a to the growing Latin American market, where regulatory support is accelerating adoption.
Sustainability & Growth Initiatives:
- Expansion of production facilities in Mexico to meet local demand.
- Development of a sustainability framework for refrigerant lifecycle management.
- Collaboration with local governments to promote low‑GWP solutions.
9️⃣ A‑Gas
Headquarters: London, United Kingdom
Key Offering: High‑purity HFO blends, safety‑certified lubricants, OEM support
A‑Gas specializes in delivering high‑purity refrigerant blends that meet stringent safety standards, making it a preferred supplier for OEMs seeking compliance with evolving regulations.
Sustainability & Growth Initiatives:
- Investment in R&D to produce ultra‑high‑purity grades.
- Collaboration with European regulators to align product specifications.
- Expansion of distribution channels across the UK and EU.
🔟 Precision (United Kingdom)
Headquarters: Birmingham, United Kingdom
Key Offering: Low‑GWP refrigerant blends, retrofit kits, technical support
Precision’s focus on precision engineering and safety certifications makes it a trusted partner for commercial refrigeration retrofits, especially in the UK and Ireland.
Sustainability & Growth Initiatives:
- Development of a comprehensive training program for technicians on R‑449a handling.
- Investment in digital monitoring solutions for system performance.
- Strategic partnership with OEMs to embed R‑449a in new equipment.
Download FREE Sample Report
Get Full Report
Outlook
Between 2026 and 2034, the R‑449a refrigerant market is expected to maintain steady growth driven by regulatory mandates and the shift towards energy‑efficient cooling solutions. The transition from high‑GWP refrigerants to low‑GWP alternatives will continue to be the primary catalyst, with new installations and retrofit projects providing the bulk of demand. The market will also benefit from technological advancements in leak detection, monitoring, and retrofit protocols that reduce the complexity and cost of adoption.
Future Trends
- Capacity Expansion and Supply‑Chain Diversification: Leading manufacturers will expand production capacity and diversify geographic footprints to mitigate supply‑chain risks and meet regional demand.
- Application‑Specific Formulations: Development of tailored blends for industrial, automotive, and residential applications will enhance performance and broaden adoption.
- Service‑Based Business Models: Companies offering training, diagnostics, and retrofit solutions will capture a growing aftermarket share.
- Strategic Partnerships: Collaboration between chemical producers, OEMs, and end‑users will drive standardization and accelerate market penetration.
- Regulatory Harmonization: Continued alignment of global regulations will reduce uncertainty and encourage long‑term investment.
- Top 10 Companies in the Global Epoxy Foam Market (2026): Market Leaders Driving Innovation - October 8, 2026
- Top 10 Companies in the Global Metallized Base Film Market (2026): Market Leaders Driving Innovation - October 8, 2026
- Top 10 Companies in the Global Nanosilver Market (2026): Market Leaders Powering Global Innovation - October 8, 2026