





MARKET INSIGHTS
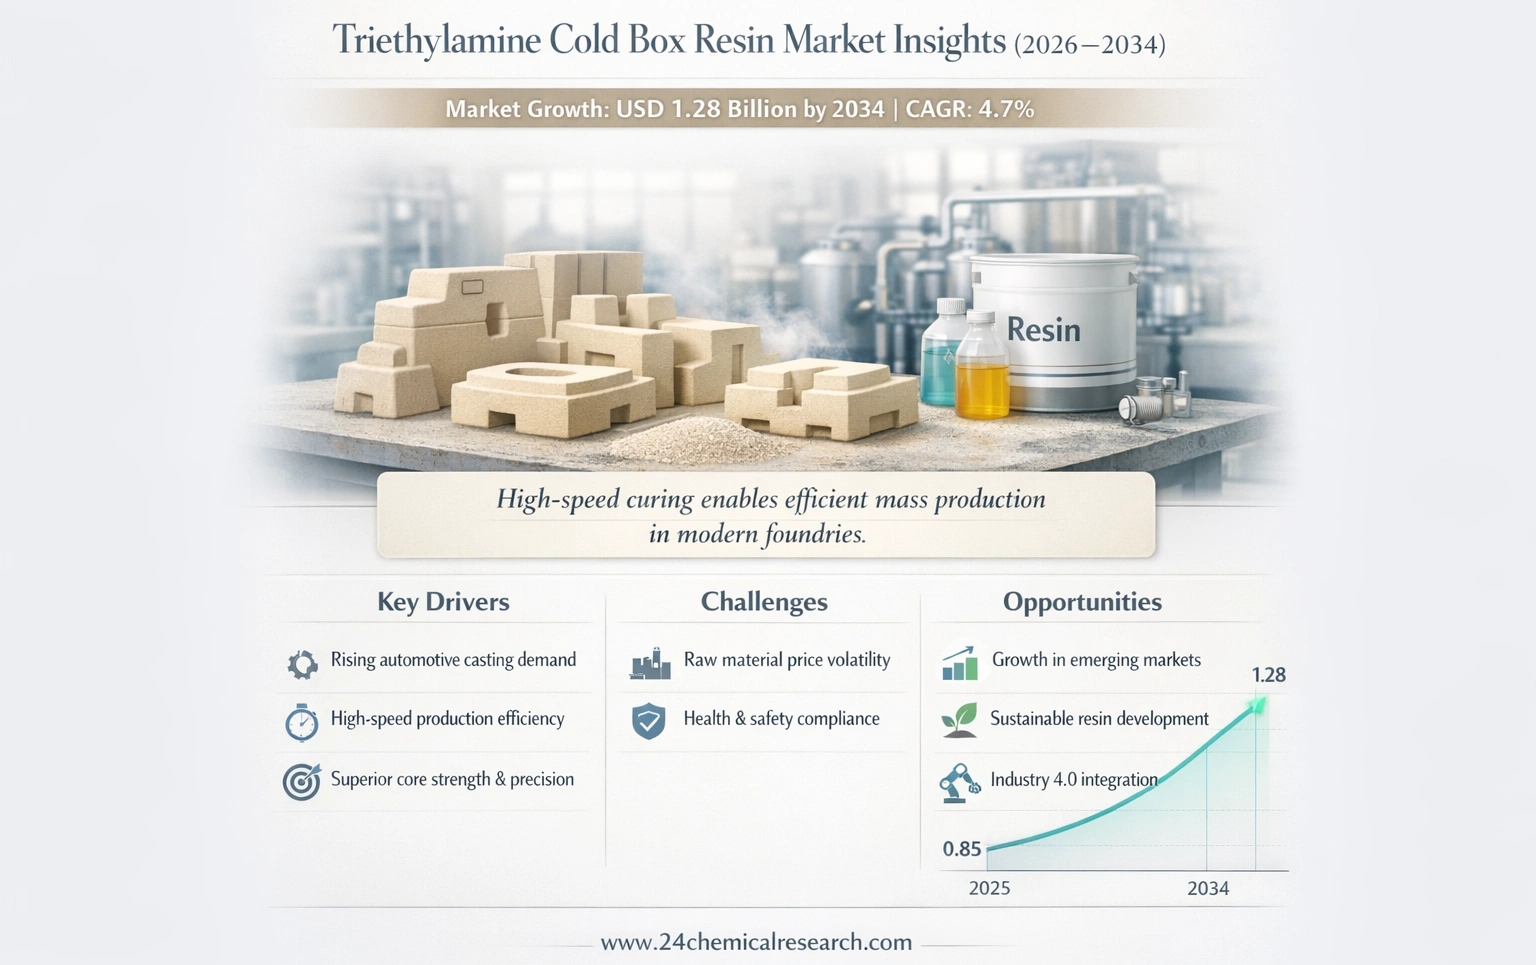
Global Triethylamine Cold Box Resin market was valued at USD 0.85 billion in 2025. The market is projected to grow from USD 0.89 billion in 2026 to USD 1.28 billion by 2034, exhibiting a CAGR of 4.7% during the forecast period.
Triethylamine Cold Box Resin is a two‑part, chemically bonded binder system fundamental to the phenolic urethane cold box process, the most widely adopted cold core box core‑making technology in foundries. This system consists of a phenolic resin (Part I) and a polyisocyanate (Part II) which, when mixed with sand and catalyzed by vaporized triethylamine, rapidly polymerise to form a high‑strength urethane bond. The process enables the production of complex, dimensionally accurate sand cores at room temperature, essential for creating internal cavities in metal castings for industries such as automotive and heavy machinery.
MARKET DRIVERS
Robust Demand from Foundry Industry
The market is primarily propelled by sustained growth in the foundry and metal casting sector. The resin system is integral to manufacturing complex, dimensionally accurate sand cores used in engine blocks, cylinder heads, and other automotive components. The global production of approximately 80 million vehicles underpins steady consumption of TEA cold box resin.
Technological Superiority over Alternative Binders
TEA‑cured phenolic urethane systems deliver superior core strength, minimal veining, and high dimensional stability, critical for intricate castings. These attributes enable higher production speeds and extended shelf‑life of prepared cores, boosting foundry productivity. The shift toward complex, high‑performance metal parts in aerospace and heavy machinery further consolidates the technology’s position.
➤ The rapid curing process, often completing within seconds, allows for high‑volume production cycles that are essential for meeting just‑in‑time manufacturing schedules in the automotive sector.
Environmental and regulatory factors also play a role. While traditional binder systems can emit higher levels of volatile organic compounds (VOCs), modern TEA cold box formulations have been engineered to be more environmentally compliant, aligning with stringent global emission standards and supporting market adoption.
MARKET CHALLENGES
Volatile Raw Material Costs and Supply Chain Disruptions
The market is sensitive to price fluctuations of key raw materials—primarily isocyanates, phenolic resins, and triethylamine—subject to volatile crude oil prices and supply chain constraints. Geopolitical tensions and logistical bottlenecks can trigger price spikes and availability issues, directly impacting profit margins of resin manufacturers and operating costs for foundries. This volatility complicates long‑term budgeting and cost control across the value chain.
Other Challenges
Health, Safety, and Environmental Regulations
Handling triethylamine, a volatile and flammable amine, requires stringent safety protocols, including proper ventilation and personal protective equipment. Regulatory bodies are increasingly focusing on workplace exposure limits and VOC emissions from foundry processes. Compliance with evolving regulations such as REACH in Europe necessitates continuous investment in safer handling systems and potentially more expensive, low‑emission resin formulations.
Competition from Alternative Binder Technologies
TEA cold box, while mature and reliable, competes with newer, more environmentally friendly binder systems—such as inorganic binders (e.g., silicate‑based) and amine‑free organic systems. These alternatives address VOC and odor issues associated with amine catalysts. Their growing adoption, especially in regions with strict environmental laws, poses a challenge to the market share of traditional TEA cold box resins.
MARKET RESTRAINTS
Shift Towards Alternative Manufacturing Processes
A gradual shift toward alternative production methods—investment casting, die casting, additive manufacturing—reduces reliance on sand casting. While sand casting remains dominant for large, complex ferrous parts, the rise of these competing technologies could limit the addressable market for cold box resins, particularly for smaller, non‑ferrous components.
Economic Cyclicality of End‑Use Industries
The market’s health is intrinsically linked to the performance of its primary end‑use industries—automotive and heavy machinery. These sectors are highly cyclical and sensitive to global economic conditions. During downturns, reduced consumer spending on vehicles and decreased capital investment in industrial machinery lower production volumes in foundries, adding unpredictability to TEA cold box resin demand.
MARKET OPPORTUNITIES
Expansion in Emerging Economies
Significant growth opportunities exist across Asia Pacific, Latin America, and Eastern Europe. Rapid industrialisation, rising automotive production, and infrastructure development in India, China, Mexico, and Thailand drive new foundry establishment and modernisation. These regions offer less saturated markets and growing demand for metal cast components, creating a favourable environment for efficient cold box technologies. Asia Pacific alone accounts for over 60 % of global casting production.
Development of Bio‑based and Sustainable Formulations
Growing demand for greener manufacturing fuels the development of bio‑based polyols and resins derived from renewable sources, and formulations with reduced amine content or lower VOC emissions. Foundries increasingly seek environmentally compliant solutions to meet corporate sustainability goals and regulatory requirements. Companies pioneering these advanced, eco‑friendly products can capture a premium market segment and build a strong competitive advantage.
Integration with Industry 4.0 and Automation
Integrating cold box core‑making processes with Industry 4.0 technologies—automated core shooting machines, real‑time process monitoring sensors, and data analytics—optimises resin usage, improves core quality consistency, and reduces waste. Suppliers offering smart resin systems compatible with automated, data‑driven production lines are well positioned to serve the modern, high‑efficiency foundries of the future.
Segment Analysis:
| Segment Category | Sub‑Segments | Key Insights |
| By Type |
|
Environmentally Friendly Type is gaining significant traction due to increasing environmental regulations and sustainability initiatives in foundry operations. This segment offers reduced VOC emissions while maintaining core strength properties comparable to conventional formulations. |
| By Application |
|
Iron Castings represents the dominant application owing to the material’s widespread use in automotive components and machinery parts. The cold box process is particularly valued for producing complex iron casting geometries with excellent dimensional accuracy and surface finish requirements. |
| By End User |
|
Automotive Foundries maintain strong demand for TEA cold box resins as they require high‑precision cores for engine blocks, transmission cases, and other critical components. The fast curing properties enable high‑volume production that matches automotive manufacturing cycles. |
| By Process |
|
Phenolic Urethane Process remains the industry standard due to its excellent balance of core strength, thermal stability, and production efficiency. Recent advancements focus on optimizing catalyst systems to improve workplace safety while maintaining rapid curing characteristics. |
| By Curing Method |
|
Gas Curing continues to dominate the market as it provides uniform catalyst distribution throughout complex core geometries. Emerging vapor‑assisted technologies are gaining attention for their potential to reduce triethylamine consumption while maintaining consistent cure quality. |
COMPETITIVE LANDSCAPE
Key Industry Players
Global Leaders Driving Innovation in Triethylamine Cold Box Resin Technology
The market features a mix of established chemical manufacturers and specialised foundry material suppliers. Hüttenes‑Albertus (Germany) and ASK Chemicals (Germany) lead through technological expertise in binder systems, dominating the premium segment with high‑performance formulations for automotive castings. Chinese manufacturers such as Xingye Materials Technology gain market share through cost‑effective solutions. The industry maintains moderate consolidation, with the top five players holding significant collective market share as of 2025.
Emerging competition comes from environmentally focused manufacturers such as Shengquan Group (China), which has invested in low‑emission formulations to meet stringent environmental regulations in North America and Europe. Japanese specialty chemical producers like Asahi Yukizai develop advanced catalyst systems, while regional foundry solution providers such as IVP (Italy) and United Erie (USA) cater to local manufacturing clusters with customised resin blends for specific metal casting applications.
List of Key Triethylamine Cold Box Resin Companies Profiled
-
Hüttenes‑Albertus (Germany)
-
ASK Chemicals (Germany)
-
Xingye Materials Technology (China)
-
Shengquan Group (China)
-
Vesuvius Group (UK)
-
Asahi Yukizai (Japan)
-
IVP (Italy)
-
United Erie (USA)
-
Furtenbach (Austria)
-
F.lli Mazzon (Italy)
-
REFCOTEC (Germany)
Triethylamine Cold Box Resin Market Trends
Growing Demand for Environmentally Friendly Resins
The market is experiencing significant growth in environmentally friendly product variants. These formulations reduce volatile organic compound (VOC) emissions during the core‑making process while maintaining performance characteristics. The segment is projected to grow at a higher CAGR compared to traditional resins, driven by tightening environmental regulations in major manufacturing regions including Europe and North America.
Other Trends
Expansion in Emerging Markets
Asia‑Pacific countries, particularly China and India, are witnessing accelerated adoption of TEA cold box resins due to growing foundry activities. The region’s steel and iron casting production expansion continues to drive demand for efficient core‑making solutions. Local manufacturers are investing in production capacity to meet both domestic needs and export opportunities.
Technological Advancements in Binder Systems
Recent innovations focus on improving binder chemistry to enhance sand core strength and reduce curing times. Manufacturers are developing modified phenolic urethane systems that maintain dimensional stability while allowing for lower catalyst usage. Additionally, research efforts are underway to optimise the triethylamine catalyst delivery systems for more consistent core quality.
Market Consolidation Among Key Players
The competitive landscape shows continued consolidation, with leading companies pursuing strategic acquisitions to expand their product portfolios and geographic reach. Established players are focusing on vertical integration strategies to secure raw material supplies and optimise production costs in response to fluctuating isocyanate pricing.
Application‑Specific Resin Development
Manufacturers are increasingly tailoring formulations for specific casting applications. Different variants are being developed for steel, iron, and non‑ferrous metal castings, each optimised for the respective metal pouring temperatures and gating system requirements. This trend is particularly evident in the automotive components segment where precision casting demands continue to rise.
Regional Analysis: Triethylamine Cold Box Resin Market
China holds the largest market share in Asia‑Pacific, with domestic manufacturers expanding production capabilities to meet both local and export demand for TEA cold box resins.
Japanese foundries demonstrate highest technology adoption rates, with stringent quality requirements driving demand for high‑performance cold box resin systems in precision casting applications.
The region benefits from concentrated resin production facilities, with major manufacturers operating integrated plants serving both domestic markets and global supply chains.
Environmental regulations in South Korea and Japan are pushing development of more sustainable cold box resin formulations, influencing product innovation across the region.
North America
The North American market features advanced foundry operations with preference for high‑efficiency cold box resin systems. The U.S. maintains significant demand from automotive and heavy equipment manufacturers, with emphasis on process consistency and environmental compliance. Technological collaborations between resin manufacturers and foundries drive product optimisation. The market sees steady adoption of environmentally friendly formulations, supported by regional regulatory frameworks and end‑user sustainability initiatives.
Europe
Europe’s mature foundry industry focuses on high‑value casting applications, sustaining demand for premium TEA cold box resins. Germany leads regional consumption, with automotive sector requirements influencing product specifications. The EU’s chemical regulations shape material development priorities, promoting low‑emission resin systems. Eastern European markets show growing adoption as manufacturing capabilities expand, while Western Europe maintains focus on advanced resin technologies for precision casting applications.
South America
Brazil represents the largest market in South America, driven by domestic automotive and machinery production. Foundries are gradually modernising operations, increasing adoption of cold box resin technologies. The region faces challenges in technical expertise and supply chain development, but shows potential for growth as local manufacturers increasingly recognise productivity benefits of advanced resin systems.
Middle East & Africa
The market in this region remains developing, with concentrated demand from oil & gas equipment manufacturing and infrastructure projects. Turkey and South Africa demonstrate relatively more advanced foundry capabilities. Market growth is constrained by limited local resin production, with most supply imported from global manufacturers. Emerging environmental awareness is beginning to influence product selection criteria among larger foundry operations.
Report Scope
This report presents a comprehensive analysis of the global and regional markets for Triethylamine Cold Box Resin, covering the period from 2025 to 2034. It includes detailed insights into the current market status and outlook across various regions and countries, with specific focus on:
-
Sales, sales volume, and revenue forecasts
-
Detailed segmentation by type and application
In addition, the report offers in-depth profiles of key industry players, including:
-
Company profiles
-
Product specifications
-
Production capacity and sales
-
Revenue, pricing, gross margins
-
Sales performance
It further examines the competitive landscape, highlighting the major vendors and identifying the critical factors expected to challenge market growth.
As part of this research, we surveyed Triethylamine Cold Box Resin companies and industry experts. The survey covered various aspects, including:
-
Revenue and demand trends
-
Product types and recent developments
-
Strategic plans and market drivers
-
Industry challenges, obstacles, and potential risks
FREQUENTLY ASKED QUESTIONS:
What is the current market size of Triethylamine Cold Box Resin Market?
-> The Triethylamine Cold Box Resin Market was valued at USD 0.85 billion in 2025 and is expected to reach USD 1.28 billion by 2034, at a CAGR of 4.7% during the forecast period.
Which key companies operate in Triethylamine Cold Box Resin Market?
-> Key players include Hüttenes‑Albertus, Xingye Materials Technology, Shengquan Group, ASK Chemicals, Vesuvius Group, Asahi Yukizai, IVP, United Erie, Furtenbach, and F.lli Mazzon, among others.
What are the key growth drivers of Triethylamine Cold Box Resin Market?
-> Key growth drivers include increasing demand for metal castings, advancements in foundry technologies, and the adoption of environmentally friendly resin types.
Which region dominates the market?
-> Asia is the fastest‑growing region, with China being a significant market, while North America remains a dominant player.
What are the emerging trends?
-> Emerging trends include development of environmentally friendly resin types, automation in core‑making processes, and sustainable foundry solutions.
Triethylamine Cold Box Resin Market – View in Detailed Research Report
Triethylamine Cold Box Resin Market – View in Detailed Research Report
- Rubber Grommets Market 2026: Leading Players Power Global Growth - October 5, 2026
- Top 10 Companies in the Natural Ethyl 2-Methylbutyrate Market (2026): Market Leaders Powering Flavor Innovation - October 5, 2026
- Top 10 Companies in the Magnesium Methoxide Market (2026): Market Leaders Powering Global Chemical Applications - October 5, 2026