





MARKET INSIGHTS
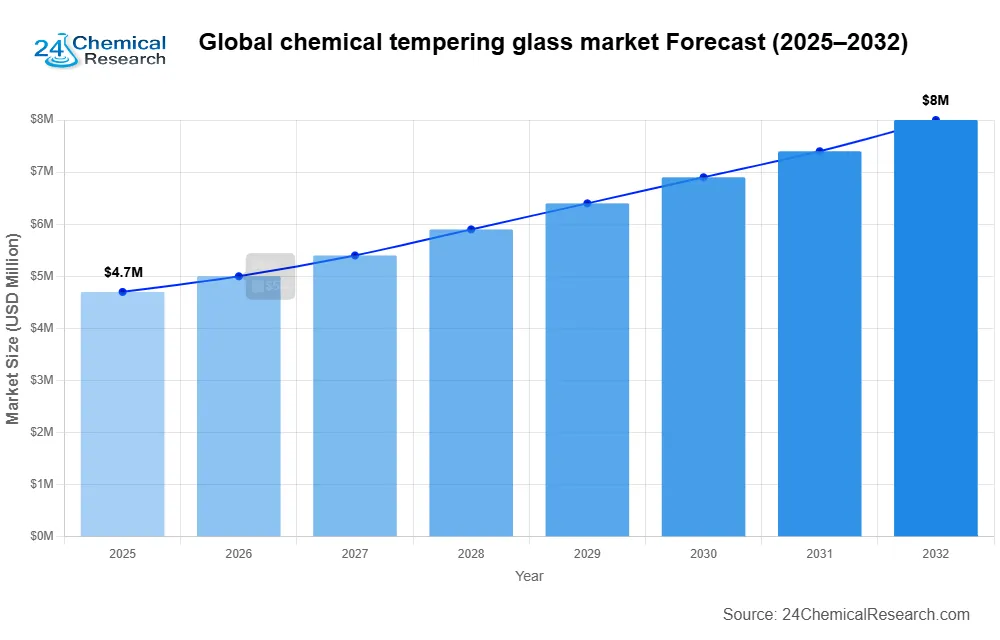
Global chemical tempering glass market size was valued at USD 4.67 billion in 2025 and is projected to reach USD 7.89 billion by 2034, growing at a CAGR of 8.0% during the forecast period. While North America remains a dominant player, the Asia‑Pacific region is expected to witness the fastest growth due to rapid industrialization and increasing smartphone penetration.
Chemical tempering glass, also known as ion‑exchange strengthened glass, undergoes a specialized process where sodium ions are replaced with larger potassium ions through immersion in a molten salt bath. This creates a durable compressive surface layer that enhances impact resistance and thermal stability compared to conventional glass. The technology finds widespread applications in automotive windshields, electronic device screens, and architectural glazing where safety and durability are paramount.
The market growth is primarily driven by expanding automotive production and rising demand for scratch‑resistant displays in consumer electronics. However, high production costs and complex processing requirements present challenges for widespread adoption. Key industry players like Corning Incorporated and AGC Inc. are investing heavily in R&D to develop more cost‑effective solutions while maintaining superior performance characteristics.
Chemical Tempering Glass Market – View in Detailed Research Report
MARKET DYNAMICS
MARKET DRIVERS
Growing Demand for Smartphones and Wearables Accelerates Market Adoption
The consumer electronics sector’s rapid expansion is the principal catalyst for the chemical tempering glass market, with smartphone manufacturers increasingly adopting chemically strengthened glass to meet durability expectations. Over 1.5 billion smartphones are shipped annually worldwide, and premium models are now standard with chemically tempered glass on both front and back panels. The rise of wearables, projected to grow at more than 15% CAGR, further fuels the need for scratch‑resistant and impact‑resistant glass. Bezel‑less designs and foldable displays in premium devices amplify the importance of advanced glass solutions that can withstand repeated bending while preserving structural integrity.
Automotive Industry’s Shift to Larger Displays Creates Sustained Demand
Modern vehicles now feature an average of 5–7 touchscreen displays per car, compared with just 1–2 a decade ago. This shift toward digital cockpits, central control panels, and rear‑seat entertainment systems requires glass that delivers optical clarity and exceptional durability. Regulatory emphasis on driver safety pushes automotive OEMs toward chemically tempered glass, which maintains visibility after minor impacts that would shatter conventional glass. Luxury electric vehicles are especially driving adoption, with panoramic roofs and interactive surfaces throughout the cabin increasingly employing chemically tempered glass.
Architectural Applications Present New Growth Avenues
The construction industry’s preference for glass facades and structural glazing systems is opening new frontiers for chemical tempering technology. Building codes in earthquake‑prone regions now mandate safety glass, and chemically tempered solutions outperform traditional thermally tempered alternatives. Commercial real‑estate developers are attracted to ultra‑clear glass panels that meet stringent safety requirements without compromising aesthetics. The technology’s ability to strengthen ultra‑thin glass (below 3 mm) has also enabled curved glass installations and interior design elements previously unattainable with conventional tempering methods.
MARKET RESTRAINTS
High Production Costs and Energy Intensiveness Limit Market Penetration
The chemical tempering process involves significant operational costs that challenge market expansion, especially in price‑sensitive segments. Large quantities of specialized potassium nitrate salts must be maintained at precise temperatures for extended periods, leading to substantial energy consumption. These factors make chemically tempered glass approximately 30–40% more expensive than standard annealed glass, creating a barrier for mass‑market adoption. Mid‑range consumer electronics manufacturers often hesitate to adopt this technology due to tight profit margins, while automotive OEMs face challenges in scaling it across economy vehicle segments.
Technical Limitations in Thickness Range Constrain Application Scope
While chemical tempering excels with thin glass applications, the technology faces inherent limitations when working with thicker panels. The ion‑exchange process gradually becomes less effective as glass thickness increases beyond 6 mm, as the compressive stress layer cannot sufficiently penetrate deeper sections of the material. This constraint makes the technology unsuitable for many architectural and automotive applications requiring thicker glass for structural purposes, especially laminated safety glass needed in hurricane‑prone regions or high‑security environments.
MARKET CHALLENGES
Supply Chain Vulnerabilities Impact Raw Material Availability
The chemical tempering industry faces mounting challenges from global supply‑chain disruptions affecting critical raw materials. Potassium nitrate, the primary chemical agent used in the ion‑exchange process, has experienced significant price volatility due to geopolitical tensions and export restrictions in key producing countries. This volatility creates unpredictable production costs that manufacturers struggle to mitigate, particularly for long‑term contracts with fixed pricing. The industry also faces challenges in securing consistent supplies of high‑purity glass substrates, as quality variations can dramatically impact the effectiveness of the chemical strengthening process.
Environmental Regulations Add Compliance Complexity
Increasingly stringent environmental regulations surrounding chemical handling and waste disposal present growing operational challenges. The chemical tempering process generates spent salt baths containing various metal ions that require specialized treatment before disposal. Regulatory frameworks in developed markets continue to tighten restrictions on industrial chemical usage and wastewater emissions, forcing manufacturers to invest heavily in advanced filtration and recycling systems. These compliance costs are particularly burdensome for small‑to‑medium enterprises seeking to enter the market, creating a competitive advantage for larger players with established environmental management systems.
MARKET OPPORTUNITIES
Emerging Flexible Display Technologies Create New Application Frontiers
The rapid development of foldable and rollable display technologies presents transformative opportunities for chemically tempered glass manufacturers. As display OEMs push the boundaries of flexible electronics, demand grows for ultra‑thin glass that can withstand hundreds of thousands of bending cycles without compromising optical performance. Chemically strengthened glass has emerged as the leading solution for these applications, offering the necessary combination of flexibility and durability that organic polymer alternatives cannot match. Industry estimates suggest the flexible display glass market could grow tenfold over the next five years, creating substantial revenue potential for manufacturers that can master the specialized chemical strengthening techniques required for these ultra‑thin formats.
Medical Device Innovations Drive Specialty Glass Demand
The medical technology sector’s increasing reliance on glass‑based components opens promising new markets for chemically tempered solutions. Applications ranging from surgical instrument panels to diagnostic equipment windows require glass that can withstand repeated sterilization cycles while maintaining optical clarity. The pharmaceutical industry’s growing adoption of pre‑filled syringes with glass barrels presents another high‑growth opportunity, where chemical tempering helps prevent breakage during automated filling and packaging processes. These medical applications typically command premium pricing with stringent quality requirements, creating favorable conditions for manufacturers that can meet the sector’s exacting standards.
Segment Analysis:
By Type
Low Temperature Chemical Tempering Glass Gains Traction Due to Energy Efficiency and Cost Advantages
The market is segmented based on type into:
- Low Temperature Chemical Tempering Glass
- High Temperature Chemical Tempering Glass
By Application
Smartphones Segment Leads the Market Due to Rising Demand for Durable Display Glass
The market is segmented based on application into:
- Automobile (windshields, sunroofs)
- Railway and Aviation (windows, panels)
- Smartphones (display covers)
- Wearables (smartwatch screens)
- Others (medical devices, architectural glass)
By End User
Consumer Electronics Sector Dominates Owing to High Adoption in Devices
The market is segmented based on end user into:
- Consumer Electronics Manufacturers
- Automotive OEMs
- Aerospace Companies
- Construction Firms
- Medical Device Manufacturers
COMPETITIVE LANDSCAPE
Key Industry Players
Strategic Innovations and Expansion Drive Market Competition
Global chemical tempering glass market exhibits a moderately consolidated landscape, dominated by established glass manufacturers with extensive technological expertise and global distribution networks. AGC Inc. (formerly Asahi Glass Co.) currently leads the sector, holding approximately 18‑20% market share through its Automotive Glass division. The company’s dominance stems from its vertically integrated production capabilities and strategic partnerships with automotive OEMs across Europe and Asia‑Pacific.
Other major players like Saint‑Gobain and NSG Group (Nippon Sheet Glass) have maintained strong positions by focusing on high‑value applications in architectural glass and specialty displays. Saint‑Gobain’s recent €50 million investment in expanding its chemical tempering facilities in France exemplifies how industry leaders are scaling production to meet growing demand for strengthened glass in consumer electronics.
The competitive intensity is further heightened by emerging Asian manufacturers like Central Glass Co., Ltd. and Shenzhen Jimy Glass, who are gaining traction through cost‑effective production methods. Meanwhile, technology‑focused firms such as Corning Incorporated continue to innovate, recently patenting a new ion‑exchange process that reduces tempering time by 30% while maintaining strength characteristics.
Market participants are increasingly differentiating through:
- Customized glass solutions for foldable devices
- Eco‑friendly tempering processes
- Enhanced optical clarity products
List of Key Chemical Tempering Glass Manufacturers
-
AGC Automotive (Japan)
-
NSG Group (Japan)
-
Saint‑Gobain (France)
-
Dlubak Glass (U.S.)
-
Central Glass Co., Ltd. (Japan)
-
Northglass Technologies (China)
-
Corning (U.S.)
-
Nippon Electric Glass Co.,Ltd (Japan)
-
Schott (Germany)
-
Abrisa Technologies (U.S.)
MARKET TRENDS
Surging Demand in Consumer Electronics to Drive Market Growth
Global chemical tempering glass market is experiencing robust growth, fueled primarily by rising adoption in consumer electronics. With smartphones requiring increasingly durable displays, manufacturers are turning to chemically strengthened glass to meet drop resistance and scratch protection standards. The technology’s ability to enhance surface compression up to 690 MPa makes it ideal for high‑stress applications. While traditional thermal tempering struggles with complex shapes and thin profiles, chemical tempering provides uniform strength across varied geometries—a critical advantage as devices become slimmer and more complex in design.
Other Trends
Automotive Safety Regulations Accelerate Adoption
Stringent safety norms are pushing automotive manufacturers to integrate chemically tempered glass in side windows and sunroofs. Unlike laminated glass used in windshields, side windows require breakage patterns that allow emergency exits while maintaining resistance to minor impacts. The European Union’s General Safety Regulation (GSR) standards, mandating improved occupant protection, have particularly driven demand. Major automakers now prioritize glass that can withstand pressures exceeding 200 MPa while maintaining optical clarity—specifications where chemical tempering outperforms alternatives.
Emerging Applications in Architectural Glazing
Architectural applications are emerging as a high‑growth segment, with developers specifying chemically tempered glass for frameless facades and structural glazing systems. The construction industry values its combination of mechanical strength (typically 4–5× stronger than annealed glass) and resistance to thermal stress—a critical factor for energy‑efficient buildings with large glass surfaces. Recent innovations in low‑temperature chemical tempering processes now allow treatment of coated and low‑emissivity (Low‑E) glass, unlocking new possibilities for sustainable building designs that maintain both performance and aesthetics.
Regional Analysis: Chemical Tempering Glass Market
North America
The North American chemical tempered glass market is driven by stringent safety regulations and high demand from the automotive and electronics industries. The U.S., which accounts for over 80% of regional demand, leads in adoption due to its strong manufacturing base for smartphones, wearables, and automotive displays. Recent investments in smart glass technologies and energy‑efficient building materials further propel growth. However, rising material costs and competition from alternative materials may temper expansion. Major players like Corning and AGC Automotive maintain strong R&D focus to develop next‑generation solutions for defense and aerospace applications, creating niche opportunities.
Europe
Europe’s market growth stems from its thriving automotive sector and strict product safety standards. Germany dominates with its premium automobile manufacturers requiring high‑impact resistant glass for sunroofs and displays. The EU’s circular economy action plan pushes manufacturers toward sustainable production methods, favoring chemical tempering over energy‑intensive thermal processes. Saint‑Gobain and Schott lead innovations in ultra‑thin glass for foldable devices, though high production costs limit broader adoption. The region’s focus on renewable energy also creates demand for tempered solar panel glass, presenting new avenues for market players.
Asia‑Pacific
Accounting for nearly 45% of global consumption, Asia‑Pacific remains the fastest‑growing market, led by China’s booming electronics manufacturing sector. Local manufacturers like Northglass Technologies cater to massive smartphone production demands, while Japanese firms pioneer ceramic‑reinforced glass variants. India’s rapidly expanding automotive industry drives adoption for windshield applications, though price sensitivity keeps market penetration below potential. Southeast Asian nations emerge as production hubs, leveraging lower operational costs. The region’s challenge lies in balancing quality standards with cost competitiveness amid rising raw material prices.
South America
Market development in South America remains uneven, with Brazil comprising over 60% of regional demand primarily for architectural and automotive applications. Economic instability frequently disrupts supply chains, causing reliance on imported tempered glass products. However, growing middle‑class consumption of electronics and government initiatives to modernize public transportation infrastructure offer growth prospects. Local production remains limited, with most major manufacturers operating through distribution partnerships rather than direct investments. The market shows gradual shift from basic soda‑lime glass to chemically strengthened alternatives in premium device segments.
Middle East & Africa
The MEA market, though small, demonstrates steady growth driven by construction booms in GCC countries and increasing smartphone penetration. UAE and Saudi Arabia lead in adopting high‑performance glass for luxury commercial projects, while African nations primarily import basic tempered glass products. Harsh climatic conditions create demand for durable glass solutions in automotive and architectural applications. Limited local manufacturing capabilities result in heavy reliance on imports from Europe and Asia, though some regional players like UAE‑based manufacturers are establishing chemical tempering facilities to capture growing demand from the construction sector.
Report Scope
This report presents a comprehensive analysis of the global and regional markets for Chemical Tempering Glass, covering the period from 2025 to 2034. It includes detailed insights into the current market status and outlook across various regions and countries, with specific focus on:
-
Sales, sales volume, and revenue forecasts
-
Detailed segmentation by type and application
In addition, the report offers in‑depth profiles of key industry players, including:
-
Company profiles
-
Product specifications
-
Production capacity and sales
-
Revenue, pricing, gross margins
-
Sales performance
It further examines the competitive landscape, highlighting the major vendors and identifying the critical factors expected to challenge market growth.
As part of this research, we surveyed Chemical Tempering Glass manufacturers and industry experts. The survey covered various aspects, including:
-
Revenue and demand trends
-
Product types and recent developments
-
Strategic plans and market drivers
-
Industry challenges, obstacles, and potential risks
FREQUENTLY ASKED QUESTIONS:
What is the current market size of Global Chemical Tempering Glass Market?
-> Global Chemical Tempering Glass market was valued at USD 4.67 billion in 2025 and is projected to reach USD 7.89 billion by 2034, growing at a CAGR of 8.0% during the forecast period.
Which key companies operate in Global Chemical Tempering Glass Market?
-> Key players include AGC Automotive, NSG Group, Saint‑Gobain, Dlubak Glass, Central Glass Co., Ltd., Northglass Technologies, Corning, Nippon Electric Glass Co., Ltd., Schott, and Abrisa Technologies, among others.
What are the key growth drivers?
-> Key growth drivers include increasing demand for durable glass in automotive and consumer electronics, technological advancements in glass tempering processes, and rising safety standards across industries.
Which region dominates the market?
-> Asia‑Pacific is the largest and fastest‑growing market, driven by China’s manufacturing expansion and Japan’s technological leadership, while North America remains a significant market due to automotive industry demand.
What are the emerging trends?
-> Emerging trends include development of ultra‑thin chemically tempered glass for foldable devices, eco‑friendly tempering processes, and increasing applications in renewable energy sectors.
Chemical Tempering Glass Market – View in Detailed Research Report
Chemical Tempering Glass Market – View in Detailed Research Report
- Top 10 Companies in the Flexible Silicone Rubber Heater Mat Market (2026): Leaders Driving Innovation - October 1, 2026
- Top 10 Companies in the Global Glycyrrhiza Inflata Root Extract Market (2026): Market Leaders Driving Natural Ingredient Trends - October 1, 2026
- Top 10 Companies in the (3‑Glycidyloxypropyl)triethoxysilane Market (2026): Market Leaders Driving Global Innovation - October 1, 2026