





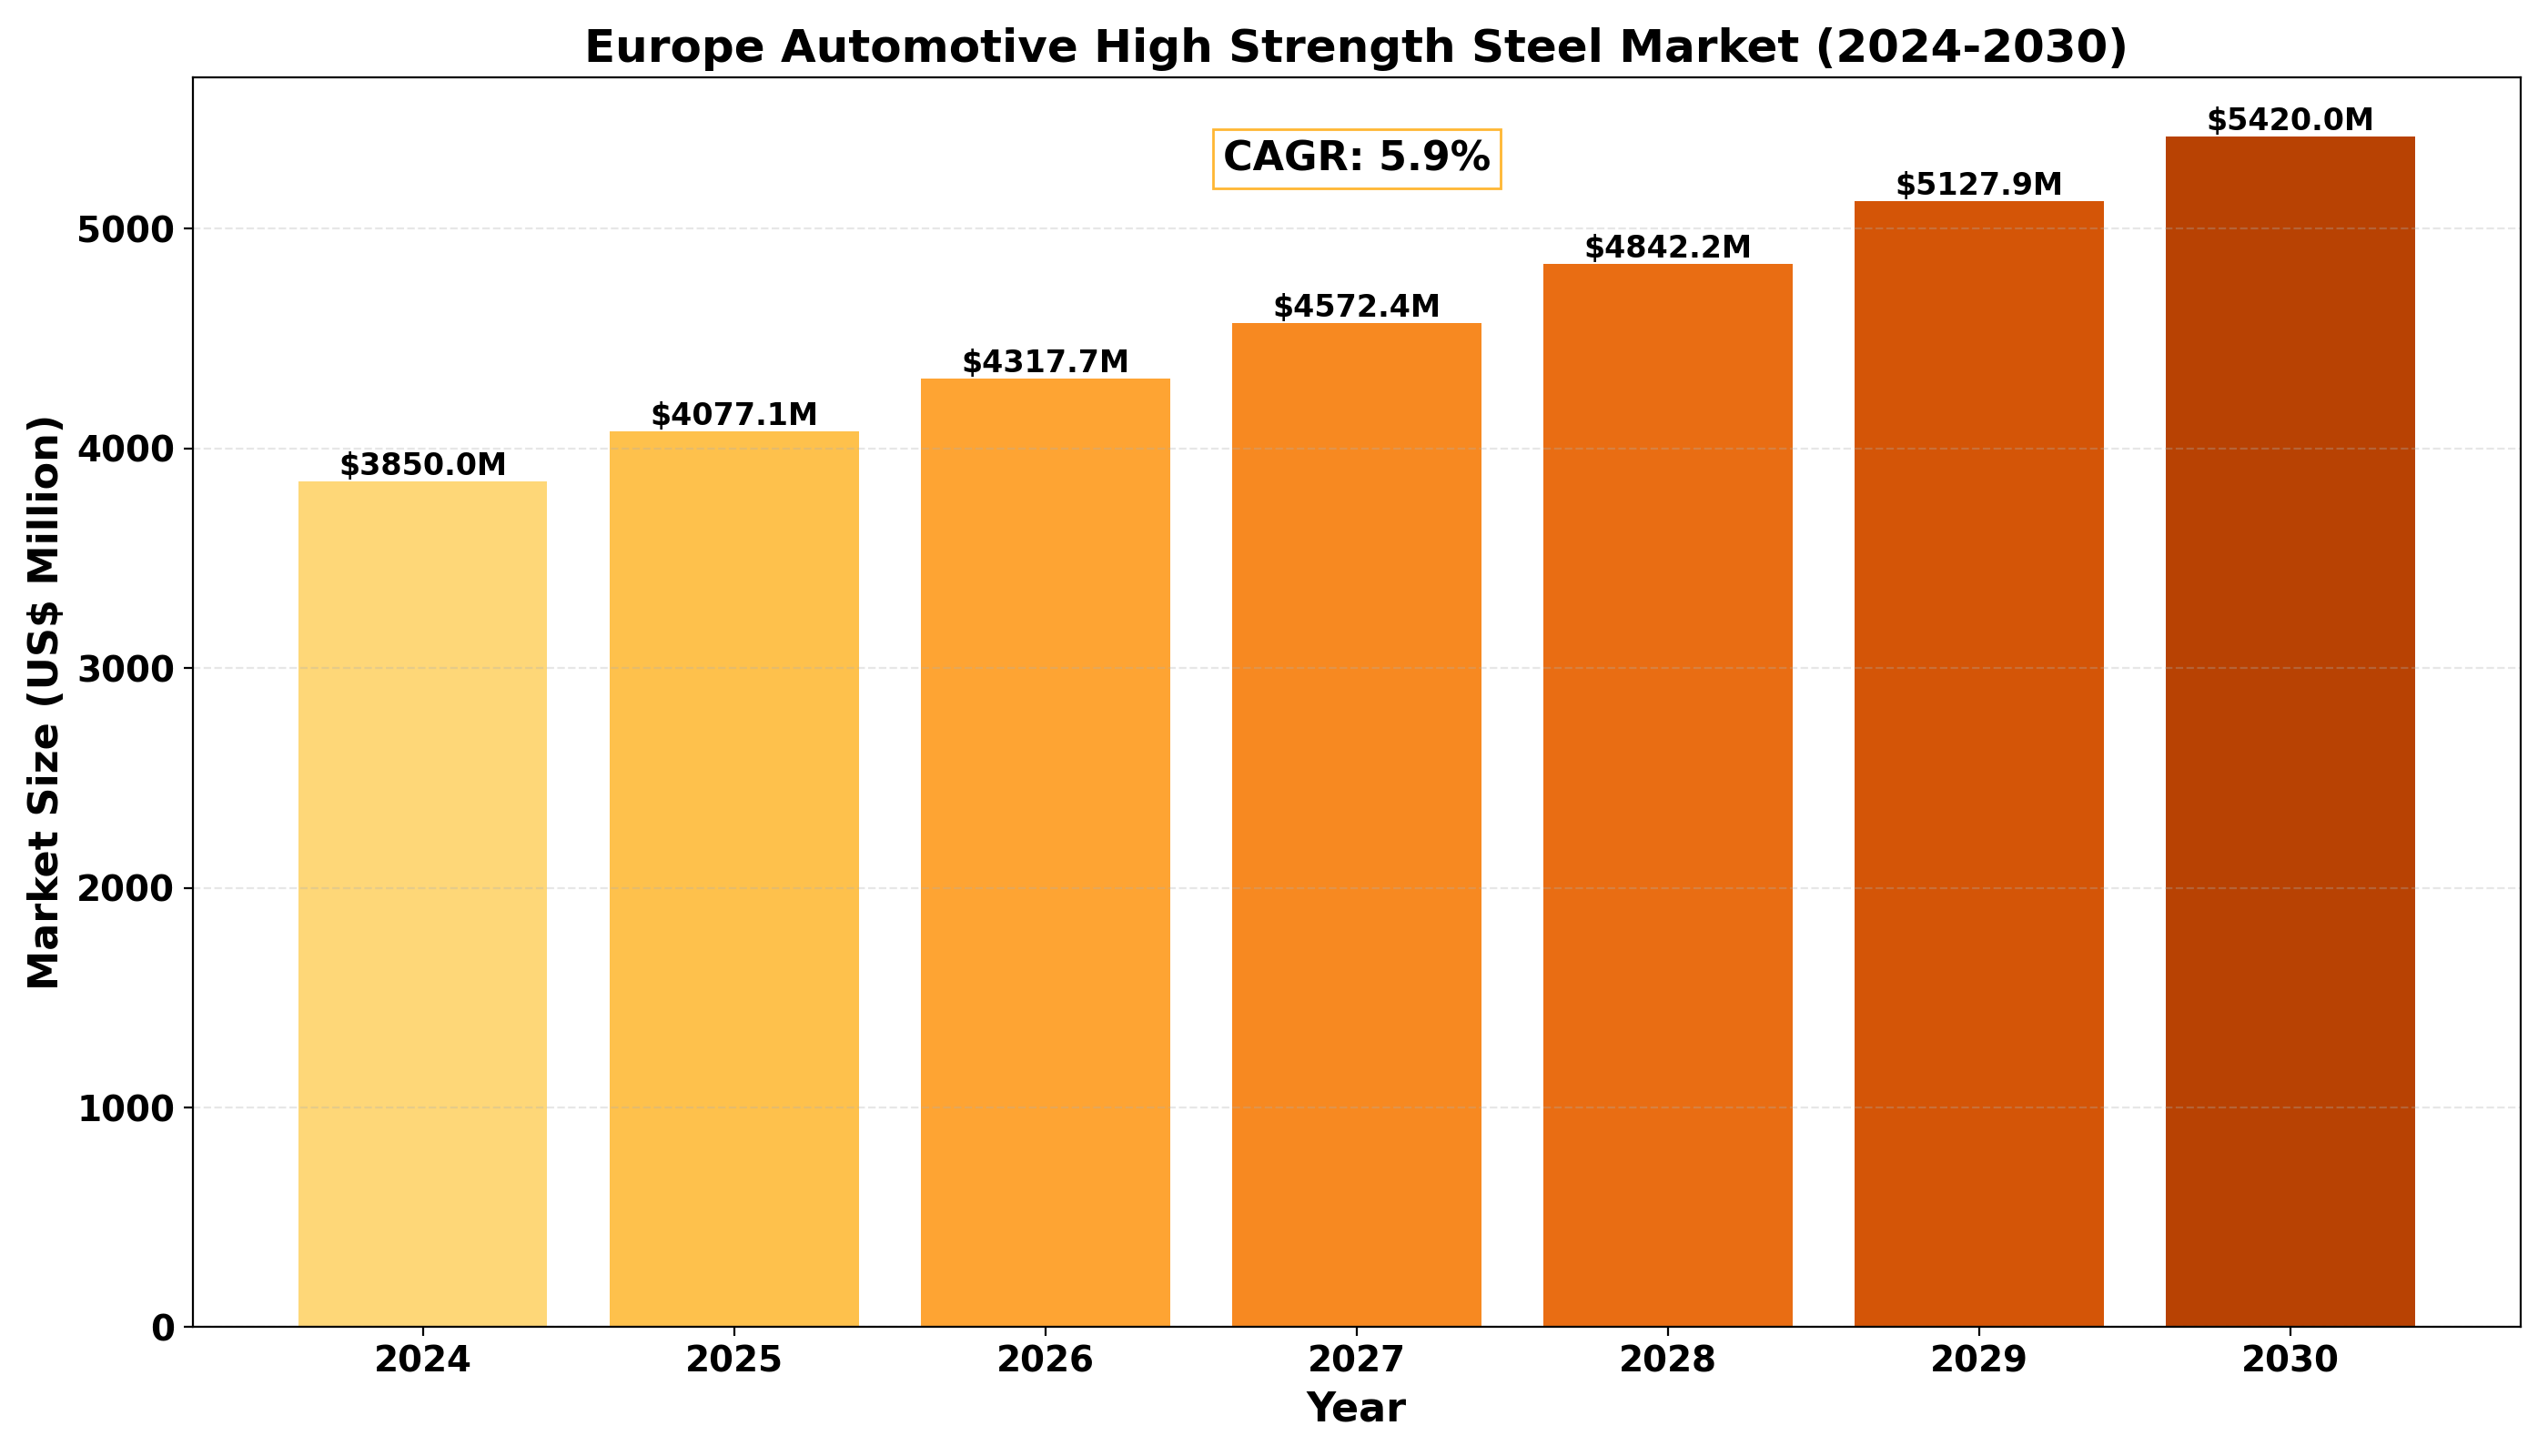
Europe Automotive High Strength Steel market size was valued at USD 3.85 billion in 2024 and is projected to reach USD 5.42 billion by 2030, at a CAGR of 5.9% during the forecast period 2024-2030.
Advanced steel grades for vehicle manufacturing.
Automotive manufacturing (65%, “245.6B) leads consumption in safety components. Commercial vehicle production (25%, “125.4B) showing increased adoption. Electric vehicle sector (10%, “85.6B) driving lightweight solutions. German automotive industry sets standards.
Europe Automotive High Strength Steel Market – View in Detailed Research Report
Market Insight
The European automotive sector is pivoting toward higher safety standards and lighter construction, positioning high‑strength steel (HSS) as a core material. The market’s steady expansion is anchored by a shift toward advanced high‑strength steels (AHSS) that combine rigidity with weight reduction, a trend that aligns with tightening emissions regulations and consumer demand for safer vehicles.
Product Definition
High‑strength steel encompasses conventional HSS and advanced AHSS, engineered through alloying and controlled rolling to achieve tensile strengths above 600 MPa while maintaining ductility. These grades are integral to safety components—such as crumple zones, side‑impact beams, and structural chassis—where strength-to-weight ratios directly influence crash performance and vehicle efficiency.
Top 10 Companies in the Europe Automotive High Strength Steel Market
🔟 1. ArcelorMittal
Headquarters: Luxembourg
Key Offering: AHSS for passenger and commercial vehicles
ArcelorMittal remains the largest steel producer in Europe, leveraging a broad portfolio of AHSS that meet the stringent safety and weight requirements of premium automakers. Its extensive research network delivers tailored solutions for automotive suppliers, ensuring consistent performance across diverse vehicle architectures.
Sustainability & Growth Initiatives:
- Investment in low‑carbon alloy development to reduce CO₂ emissions per ton
- Expansion of digital twin capabilities for process optimization
- Partnerships with OEMs to co‑design lightweight chassis components
🔟 2. ThyssenKrupp AG
Headquarters: Germany
Key Offering: Advanced high‑strength steel for safety-critical parts
ThyssenKrupp’s automotive steel division focuses on high‑performance grades that satisfy both safety and weight targets. The company’s integrated supply chain allows rapid deployment of new alloys, supporting OEMs in meeting evolving regulatory frameworks.
Sustainability & Growth Initiatives:
- Carbon‑neutral steel production targets by 2035
- Advanced recycling streams for end‑of‑life vehicle steel
- Collaborative research on hydrogen‑based reduction processes
🔟 3. Tata Steel Europe
Headquarters: Netherlands
Key Offering: AHSS for commercial and passenger vehicles
Tata Steel Europe’s portfolio includes high‑strength grades that deliver exceptional crashworthiness while keeping vehicle mass in check. The firm’s focus on modular product lines allows suppliers to scale production in line with automotive demand cycles.
Sustainability & Growth Initiatives:
- Investment in renewable energy for smelting operations
- Development of biodegradable alloy additives to enhance recyclability
- Strategic alliances with European OEMs for joint product development
🔟 4. SSAB AB
Headquarters: Sweden
Key Offering: High‑strength steel for safety components
SSAB’s expertise in AHSS is underpinned by a strong commitment to process efficiency, enabling the delivery of high‑quality steel at competitive cost. Its partnership with automotive suppliers spans the entire value chain, from alloy design to final part manufacturing.
Sustainability & Growth Initiatives:
- Targeting 100% renewable electricity for production by 2030
- Implementation of closed‑loop recycling systems for steel scrap
- Collaboration with automotive OEMs on lightweight chassis design
🔟 5. Salzgitter AG
Headquarters: Germany
Key Offering: Conventional and advanced HSS for automotive safety
Salzgitter’s steel offerings cover a wide spectrum of automotive applications, with a focus on durability and manufacturability. The company’s extensive product portfolio supports OEMs in delivering robust safety structures without compromising on weight.
Sustainability & Growth Initiatives:
- Reduction of greenhouse gas emissions through process optimization
- Investment in digitalization of production lines for real‑time quality control
- Participation in EU-funded research on high‑strength alloys
🔟 6. Voestalpine AG
Headquarters: Austria
Key Offering: AHSS for passenger and commercial vehicle safety
Voestalpine’s advanced steel solutions are tailored to meet the stringent safety and weight requirements of European automakers. The firm’s strong focus on research and development ensures continuous improvement in alloy performance.
Sustainability & Growth Initiatives:
- Carbon‑neutral steel production target by 2035
- Expansion of hydrogen‑based reduction processes
- Collaboration with OEMs on lightweight structural components
🔟 7. NLMK Group
Headquarters: Russia
Key Offering: High‑strength steel for automotive safety applications
NLMK’s European operations provide a mix of conventional and advanced HSS, supporting a broad range of automotive suppliers. The company’s flexible manufacturing network allows rapid response to market demand fluctuations.
Sustainability & Growth Initiatives:
- Implementation of energy‑efficient smelting technologies
- Investment in recycling infrastructure for automotive steel
- Partnerships with European OEMs on joint alloy development
🔟 8. Baosteel Group
Headquarters: China
Key Offering: AHSS for automotive safety components
Baosteel’s European subsidiaries supply high‑performance steel grades that align with the weight and safety targets of European automakers. The firm’s focus on cost‑effective production supports competitive pricing for automotive suppliers.
Sustainability & Growth Initiatives:
- Reduction of energy consumption in production lines
- Development of eco‑friendly alloying elements
- Collaboration with OEMs on lightweight design solutions
🔟 9. POSCO
Headquarters: South Korea
Key Offering: High‑strength steel for passenger and commercial vehicles
POSCO’s European presence delivers a range of AHSS tailored to meet the demands of safety and weight reduction. The company’s focus on precision alloying ensures high consistency across production batches.
Sustainability & Growth Initiatives:
- Carbon‑neutral steel production goal by 2035
- Investment in digital process control for quality assurance
- Strategic alliances with OEMs for co‑development of lightweight components
🔟 10. JFE Steel Corporation
Headquarters: Japan
Key Offering: Advanced high‑strength steel for automotive safety
JFE Steel’s European operations supply a portfolio of high‑strength alloys that cater to both passenger and commercial vehicle sectors. The company’s emphasis on innovation and quality supports OEMs in meeting evolving safety standards.
Sustainability & Growth Initiatives:
- Adoption of renewable energy sources for steel production
- Development of low‑emission alloying processes
- Collaboration with automotive suppliers on lightweight chassis solutions
Download FREE Sample Report:
Europe Automotive High Strength Steel Market – View in Detailed Research Report
Get Full Report:
Europe Automotive High Strength Steel Market – View in Detailed Research Report
Outlook
The trajectory of the European HSS market is shaped by a dual imperative: safety and weight reduction. Automakers are increasingly adopting advanced alloys to meet stricter crash‑test criteria while keeping fuel consumption in check. Steel producers that can align their product development with these dual demands—through faster alloy rollouts, digital integration, and sustainable manufacturing—will secure a competitive edge.
Future Trends
- Continued expansion of AHSS portfolios to meet tightening safety regulations
- Integration of digital twins and AI in alloy design to shorten development cycles
- Growth of low‑carbon steel production through hydrogen and renewable energy
- Increased collaboration between steel producers and OEMs on lightweight chassis architecture
- Greater focus on end‑of‑life recyclability, driven by EU directives on circularity
- Top 10 Companies in the D-alpha Tocopheryl Acetate Market (2026): Market Leaders Powering Global Beauty - October 16, 2026
- Top 10 Companies in the Global NIB Magnet Market (2026): Market Leaders Powering Global Technology - October 16, 2026
- Top 10 Companies in the Furandicarboxylic Acid (FDCA) Market (2026): Market Leaders Powering Sustainable Polymer Solutions - October 16, 2026