





The Global Investment Cast Superalloy market size was valued at USD 1.85 billion in 2024 and is projected to reach USD 2.65 billion by 2030, at a CAGR of 6.2% during the forecast period 2024‑2030.
The United States Investment Cast Superalloy market size was valued at USD 485.6 million in 2024 and is projected to reach USD 665.4 million by 2030, at a CAGR of 5.4% during the forecast period 2024‑2030.
Investment cast superalloys are high‑performance metal alloys produced through precision casting for aerospace and industrial applications.
Aerospace drives the majority of demand, with a production volume of 125,000 metric tons in 2023. New alloy development projects are slated to invest USD 525 million, and safety standards continue to shape the market. Aerospace accounts for 58% of total consumption, while an 85% scrap recycling rate underscores the sector’s commitment to sustainability.
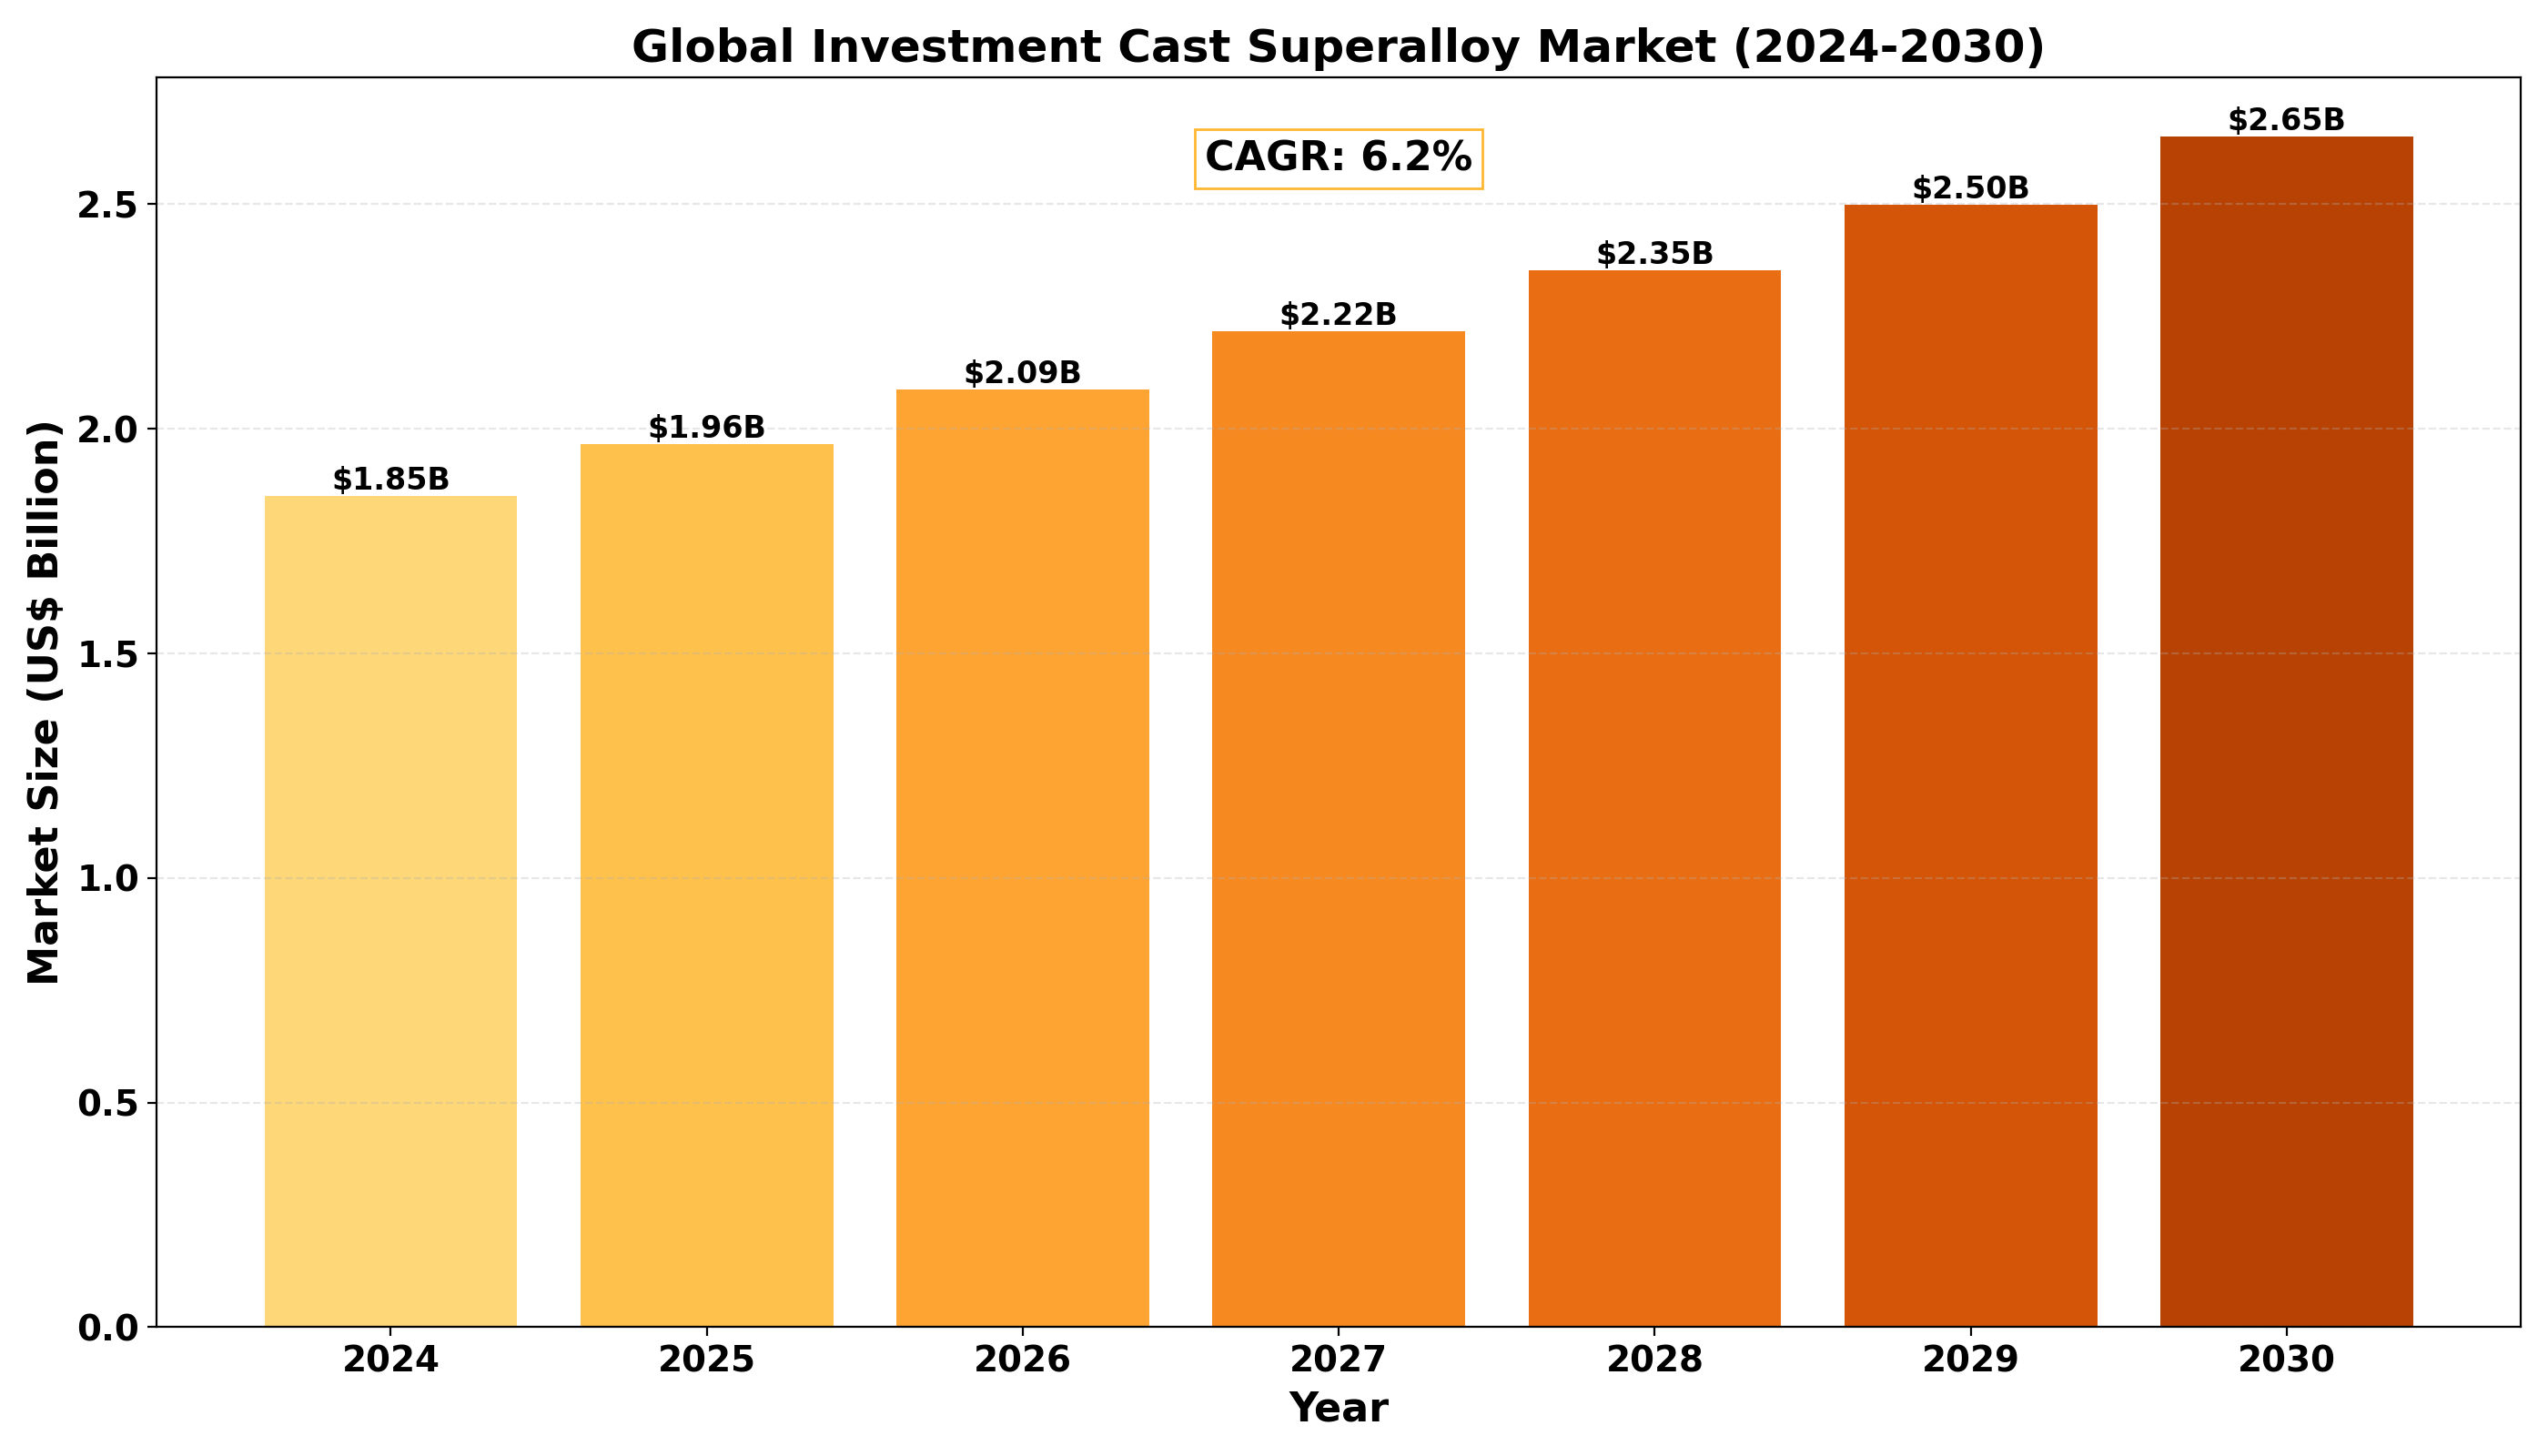
Global Investment Cast Superalloy Market – View in Detailed Research Report
Market Insight
The precision‑cast alloy segment has carved a niche within the aerospace supply chain, where reliability and performance outweigh cost considerations. Manufacturers are increasingly adopting directional solidification and single‑crystal casting to eliminate grain boundaries, thereby enhancing resistance to high temperatures and corrosive environments. The industry’s trajectory is shaped by stringent aviation safety mandates and a growing emphasis on circular economy principles, reflected in the high recycling rate.
Top 10 Companies
🔟 10. Arconic
Headquarters: Cleveland, Ohio, USA
Key Offering: Nickel‑based cast superalloys for turbine components
Arconic leverages its extensive alloy research pipeline to supply lightweight, high‑temperature materials for jet engines. The company’s recent partnership with a leading aircraft manufacturer underscores its role in next‑generation propulsion systems.
Growth Initiatives:
- Investment in additive manufacturing to reduce lead times
- Expansion of alloy development into hypersonic applications
- Strategic collaborations with aerospace OEMs to secure long‑term supply contracts
🟨 9. Rolls‑Royce
Headquarters: Birmingham, United Kingdom
Key Offering: Advanced superalloy components for commercial and military engines
Rolls‑Royce’s in‑house alloy development program focuses on enhancing durability under extreme operating conditions. Recent R&D breakthroughs in high‑entropy alloys are poised to extend component life cycles.
Growth Initiatives:
- Launch of a joint venture with a materials university for alloy innovation
- Deployment of digital twin technology to optimize casting processes
- Commitment to carbon‑neutral manufacturing by 2035
🟨 8. Precision Castparts Corp (PCC)
Headquarters: Cleveland, Ohio, USA
Key Offering: Nickel‑based superalloys for aerospace and industrial applications
PCC remains a cornerstone supplier for jet engine manufacturers, offering a broad portfolio of cast components. Its recent acquisition of a specialty alloy firm expands its capabilities in high‑temperature alloys.
Growth Initiatives:
- Integration of AI‑driven quality control in casting lines
- Expansion of service offerings to include component repair and refurbishment
- Strategic alliance with a leading additive manufacturing firm
🟨 7. Howmet Aerospace
Headquarters: Cleveland, Ohio, USA
Key Offering: Nickel‑based cast superalloys for turbine and fan blades
Howmet’s focus on lightweight alloys aligns with the industry’s push for fuel efficiency. Recent product launches include a new low‑density alloy that reduces component weight by up to 12%.
Growth Initiatives:
- Investment in research on phase‑stabilized alloys
- Expansion of global manufacturing footprint to Asia‑Pacific
- Collaboration with major OEMs on joint testing programs
🟨 6. Pratt & Whitney
Headquarters: East Hartford, Connecticut, USA
Key Offering: Proprietary superalloys for aircraft engines
Pratt & Whitney’s in‑house alloy development program drives performance gains in next‑generation engines. Recent advancements in single‑crystal casting have improved thermal efficiency.
Growth Initiatives:
- Expansion of the alloy research center in Huntsville, Alabama
- Partnerships with universities to explore high‑entropy materials
- Implementation of closed‑loop recycling for alloy scrap
🟨 5. GE Additive
Headquarters: Fairfield, Ohio, USA
Key Offering: Additive‑manufactured superalloy components
GE Additive bridges traditional casting with 3D printing, enabling complex geometries and reduced material waste. Its recent launch of a titanium‑based additive alloy line targets high‑performance aerospace parts.
Growth Initiatives:
- Expansion of additive manufacturing facilities in Europe
- Investment in post‑processing technologies to enhance surface finish
- Strategic alliance with a leading aerospace manufacturer for pilot projects
🟨 4. Allegheny Technologies Inc. (ATI)
Headquarters: Pittsburgh, Pennsylvania, USA
Key Offering: Nickel‑based and cobalt‑based superalloys
ATI’s long‑standing expertise in high‑temperature alloys supports a wide range of aerospace and power generation applications. Recent R&D initiatives focus on alloying elements that enhance corrosion resistance.
Growth Initiatives:
- Launch of a new alloy line optimized for hypersonic flight
- Expansion of the research and development center in Charlotte, North Carolina
- Partnership with a major defense contractor for joint testing
🟨 3. Cannon Muskegon
Headquarters: Muskegon, Michigan, USA
Key Offering: Nickel‑based superalloys for turbine blades and fan discs
Cannon Muskegon’s focus on high‑temperature performance has positioned it as a key supplier to major OEMs. The company recently introduced a new alloy with improved creep resistance.
Growth Initiatives:
- Investment in digital twin technology for process optimization
- Expansion of the production line to meet increasing demand
- Strategic collaboration with a leading aerospace research institute
🟨 2. Haynes International
Headquarters: Waltham, Massachusetts, USA
Key Offering: Nickel‑based superalloys for aerospace and industrial sectors
Haynes International’s portfolio includes alloys designed for extreme heat and corrosion, making it a preferred partner for aircraft engine manufacturers. Recent developments include a new alloy with enhanced oxidation resistance.
Growth Initiatives:
- Expansion of the manufacturing facility in Waltham to increase capacity
- Investment in research on next‑generation alloying elements
- Partnership with a leading aerospace OEM for joint testing
🟨 1. Special Metals Corporation
Headquarters: St. Louis, Missouri, USA
Key Offering: Nickel‑based and cobalt‑based superalloys for aerospace, power generation, and industrial markets
Special Metals Corporation’s long history in superalloy production and its focus on innovation have cemented its status as a market leader. The company recently launched a new alloy family that delivers superior strength at high temperatures.
Growth Initiatives:
- Investment in a new alloy research center in the Midwest
- Expansion of the production line in St. Louis to accommodate new product families
- Strategic partnership with a leading aerospace manufacturer to test new alloys in real‑world applications
Download FREE Sample Report: Global Investment Cast Superalloy Market – View in Detailed Research Report
Get Full Report: Global Investment Cast Superalloy Market – View in Detailed Research Report
Outlook
The aerospace segment continues to be the primary engine of demand, driven by the need for higher efficiency and stricter emission standards. As new aircraft models enter service, the requirement for lighter, more durable superalloys will intensify. Meanwhile, the industrial sector, particularly power generation and oil & gas, is beginning to adopt advanced alloys to improve operational reliability.
Future Trends
- Increased adoption of additive manufacturing to reduce material waste and enable complex geometries.
- Development of high‑entropy and multi‑component alloys to push performance boundaries.
- Greater emphasis on closed‑loop recycling and circular supply chains.
- Strategic alliances between alloy manufacturers and OEMs to secure supply and accelerate technology transfer.
- Continued regulatory pressure to meet higher safety and environmental standards, fostering innovation in alloy design.
- Top 10 Companies in the Hydrazine Hydrate and Its Derivatives Market (2026): Market Leaders Driving Global Chemical Innovation - October 15, 2026
- Top 10 Companies in the Global Deuterium (CAS 7782-39-0) Market (2026): Market Leaders Driving Innovation - October 15, 2026
- Top 10 Companies in the Global 1‑Methylpropyl Acetate Market (2026): Market Leaders Powering Global Solvents - October 15, 2026