





MARKET INSIGHTS
Global silicon carbide semiconductor material market size was valued at USD 1.98 billion in 2024 and is projected to reach USD 4.12 billion by 2032, growing at a CAGR of 11.1% during the forecast period.
Silicon carbide (SiC) semiconductor materials are advanced compound semiconductors known for their superior thermal conductivity, high breakdown voltage, and excellent power efficiency. These materials are increasingly adopted in high‑power, high‑frequency, and high‑temperature applications across industries. Key product segments include 2H‑SiC, 3C‑SiC, 4H‑SiC, and 6H‑SiC semiconductors, each offering distinct electrical properties for specialized applications.
The market growth is primarily driven by the accelerating adoption of electric vehicles (EVs), which accounted for approximately 14% of global car sales in 2023. While the automotive sector dominates demand, emerging applications in renewable energy infrastructure and 5G telecommunications are creating new growth opportunities. The industry is currently transitioning from 6‑inch to 8‑inch wafer production, with major manufacturers like Wolfspeed and STMicroelectronics leading this technological shift. China’s rapid market expansion, fueled by government support and local manufacturing initiatives, is reshaping the competitive landscape.
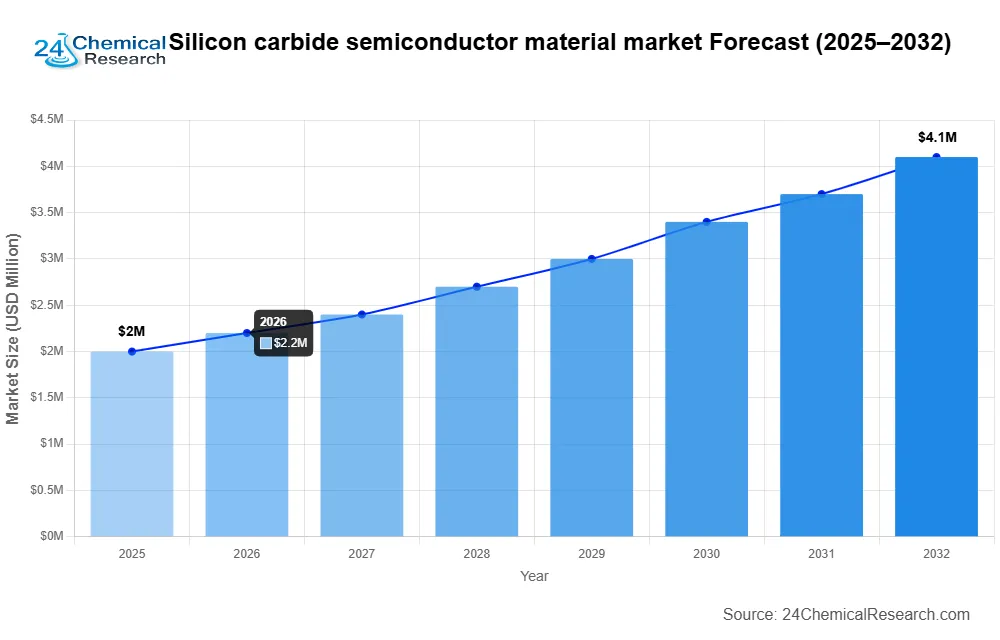
Silicon Carbide Semiconductor Material Market – View in Detailed Research Report
Top 10 Companies Driving the Silicon Carbide Semiconductor Landscape
🔟 1. Wolfspeed, Inc.
Headquarters: Santa Clara, California, USA
Key Offering: SiC substrates, power devices, and integrated modules
Wolfspeed has positioned itself as the most complete SiC ecosystem provider, coupling wafer growth with device fabrication and system‑level solutions. The company’s $1 billion expansion of its 200‑mm SiC wafer facility has cemented its capacity leadership for the next decade.
Sustainability & Growth Initiatives:
- Investing in 8‑inch wafer technology to reduce unit cost
- Partnering with OEMs to accelerate 800‑V EV powertrain adoption
- Deploying SiC in solar inverters to boost renewable yield
9️⃣ 2. Infineon Technologies AG
Headquarters: Munich, Germany
Key Offering: CoolSiC MOSFETs, SiC power modules, and automotive solutions
Infineon’s CoolSiC platform delivers high‑performance MOSFETs for EV traction inverters and DC‑DC converters. The company leverages its strong European R&D base to innovate in high‑temperature operation and reliability.
Strategic Initiatives:
- Expanding 6‑inch wafer capacity in Germany
- Collaborating with German OEMs on 800‑V battery packs
- Investing in SiC‑based smart grid solutions
8️⃣ 3. ROHM Semiconductor
Headquarters: Kyoto, Japan
Key Offering: High‑performance SiC MOSFETs for automotive and industrial markets
ROHM focuses on delivering high‑efficiency MOSFETs that meet the stringent thermal and voltage requirements of next‑generation EVs. Its strong supply chain in Japan supports rapid prototyping and scale‑up.
Innovation Highlights:
- Developing 800‑V SiC devices with reduced gate drive complexity
- Partnering with Japanese automakers on hybrid‑electric powertrains
- Expanding R&D in SiC‑based power electronics for industrial motor drives
7️⃣ 4. STMicroelectronics
Headquarters: Geneva, Switzerland
Key Offering: SiC power modules and integrated solutions for automotive and industrial sectors
STMicroelectronics is building a vertically integrated SiC stack that spans wafer growth, device fabrication, and system integration. The company is actively pursuing joint development agreements to secure long‑term material supply.
Growth Drivers:
- Expanding 6‑inch wafer capacity in Switzerland
- Collaborating with European OEMs on high‑temperature EV components
- Investing in SiC‑based power electronics for wind turbine control systems
6️⃣ 5. ON Semiconductor
Headquarters: Phoenix, Arizona, USA
Key Offering: SiC power devices, modules, and system‑level solutions
ON Semiconductor has positioned itself as a flexible partner for OEMs seeking to integrate SiC into their power architectures. The company’s focus on modularity has made it a preferred supplier for both automotive and industrial customers.
Strategic Moves:
- Acquiring substrate suppliers to secure supply chain control
- Developing SiC‑based converters for data center power supplies
- Collaborating with U.S. automakers on 800‑V battery systems
5️⃣ 6. SICC Co.
Headquarters: Shanghai, China
Key Offering: SiC wafers and power devices for automotive and renewable energy
SICC has rapidly expanded its 6‑inch wafer production, backed by strong Chinese government subsidies. The company is positioning itself as a key supplier for China’s aggressive EV and solar markets.
Key Initiatives:
- Investing in 8‑inch wafer research to reduce cost per wafer
- Forming joint ventures with Chinese automakers for SiC power modules
- Expanding its domestic supply chain to reduce lead times
4️⃣ 7. Tianyu Semiconductor
Headquarters: Shenzhen, China
Key Offering: SiC substrates and power devices
Tianyu’s strategy revolves around scaling up 6‑inch wafer output and forging partnerships with domestic OEMs. The company is also exploring collaborations with global players to share technology and mitigate IP risks.
Business Focus:
- Expanding production capacity to meet rising domestic demand
- Engaging in technology transfer agreements with international partners
- Targeting high‑margin automotive and industrial applications
3️⃣ 8. GeneSiC Semiconductor
Headquarters: San Jose, California, USA
Key Offering: SiC power devices and modules for consumer electronics and automotive markets
GeneSiC is carving out a niche by integrating GaN‑on‑SiC technology into compact power solutions for smartphones, laptops, and EV chargers. The company’s focus on miniaturization positions it well for the growing demand for efficient consumer electronics.
Innovation Highlights:
- Developing 50‑W SiC modules for high‑speed charging
- Partnering with major smartphone OEMs on next‑generation power management
- Investing in advanced packaging to improve thermal performance
2️⃣ 9. KYOCERA Corporation
Headquarters: Kyoto, Japan
Key Offering: SiC wafers, power devices, and integrated solutions for automotive and industrial sectors
KYOCERA’s long‑standing expertise in ceramics and semiconductors underpins its robust SiC portfolio. The company is actively expanding its 6‑inch wafer capacity and pursuing collaborations with European OEMs.
Strategic Initiatives:
- Investing in 8‑inch wafer technology to lower unit cost
- Partnering with Japanese automakers on high‑temperature power modules
- Developing SiC solutions for industrial motor drives and renewable energy systems
1️⃣ 10. TME
Headquarters: Shenzhen, China
Key Offering: SiC substrates and power devices for automotive and industrial applications
TME is scaling its 6‑inch wafer production while forging partnerships with domestic OEMs. The company’s focus on cost efficiency and rapid capacity expansion positions it as a key player in China’s SiC market.
Business Focus:
- Expanding 6‑inch wafer output to meet domestic demand
- Forming joint ventures with automakers for SiC power modules
- Investing in advanced packaging to reduce thermal mismatch
Download FREE Sample Report: Silicon Carbide Semiconductor Material Market – View in Detailed Research Report
Get Full Report Here: Silicon Carbide Semiconductor Material Market – View in Detailed Research Report
🌍 Outlook: The Future of Silicon Carbide Semiconductor Material Market
As electric vehicles continue to capture a growing share of global car sales, the demand for SiC power electronics will remain a primary growth engine. Simultaneously, renewable energy projects and 5G infrastructure are expanding the application horizon, providing new avenues for market expansion. The transition to 8‑inch wafers is poised to reduce production costs and improve yields, further accelerating adoption across industries.
📈 Key Trends Shaping the Market:
- Rapid electrification of automotive powertrains
- Expansion of renewable energy projects requiring high‑temperature tolerant converters
- Increasing demand for high‑frequency RF components in 5G base stations
- Vertical integration to secure supply chain resilience
- Innovation in packaging and thermal management to support higher power densities
Companies that successfully navigate the cost challenges, supply‑chain constraints, and IP fragmentation will secure a competitive edge in this high‑growth landscape.
- Top 10 Companies in the Dotted Tactile Bricks Market (2026): Market Leaders Powering Global Accessibility - October 5, 2026
- Top 10 Companies in the Corrosion Inhibiting Admixtures Market (2026): Market Leaders Driving Concrete Durability - October 5, 2026
- Top 10 Companies in the 1,2,4-Butanetriol (CAS 3068-00-6) Market (2026): Market Leaders Driving Global Demand - October 5, 2026